Key Points
- Strategic Shift: BAT is moving from category expansion toward building structural competitive moats across its portfolio.
- Vapour: Vuse Ultra leverages connected ecosystems and compliance-driven hardware to defend structurally against low-cost illicit disposables.
- Modern Oral: Velo’s product architecture is tailored to U.S. and European consumption cultures, positioning it as the primary growth engine.
- Heated Products: glo HiLo’s two-piece redesign and no-cleaning system reflect premium form factor convergence and strategic repositioning.
- Combustibles: A laddering pricing structure creates internal migration paths to retain value amid downtrading pressure.
- Operational Backbone: The Fit2Win productivity program and cost optimization fund premium innovation, reinforcing financial sustainability.
- Enforcement Variable: The profitability of BAT’s high-end innovation strategy depends heavily on consistent regulatory enforcement in key markets.
2Firsts, February 12, 2026,
British American Tobacco (BAT) held its FY2025 results call on the morning of February 12, 2026 (GMT), framing 2026 as a return to its mid-term growth algorithm while acknowledging that delivery will depend heavily on regulatory enforcement and illicit market dynamics.
Beyond the financial disclosures — including a 77% increase in New Category contribution to £442 million — management devoted significant attention to product architecture, premium innovation rollouts and enforcement dependencies across categories.
Based on the FY2025 results materials and the management Q&A session, 2Firsts has conducted an independent analysis of BAT’s evolving product strategy.
1. Vapour: From Hardware Participation to Ecosystem Defense
What BAT disclosed
BAT positioned Vuse Ultra as its most advanced vapour device . The product integrates:
- ClearView™ display
- Flavour AutoTune™ adaptive heating
- CloudControl™ vapor customization
- Device Lock and Find My Vape features
- A removable and replaceable battery
The device connects to the MYVUSE™ App, with 44% of users converting to active app users and 97% of those engaging with usage tracking .
Management linked second-half U.S. stabilization in Vapour to increased enforcement against illicit products , with the CEO stating that performance improves “once enforcement kicks in” .

2Firsts Analysis
The disclosed product features suggest that BAT is deliberately repositioning Vapour from a price-sensitive hardware category toward a consumer electronics ecosystem model.
Rather than competing directly with low-cost disposable imports on pricing, BAT appears to be constructing defensive barriers through:
1. Software ecosystem integration (App dependency increases switching cost)
2. Compliance-ready hardware design (e.g., removable batteries anticipating EU regulation)
3. Feature differentiation difficult to replicate in informal supply chains
The removable battery design, in particular, functions not only as a sustainability feature but as a regulatory gate. If regulators require removable batteries, illicit producers built around low-cost integrated designs would need to retool production lines, raising costs and operational complexity.
In this framework, Vuse’s role is defensive: to build structural insulation rather than chase share in the disposable segment.
2. Modern Oral: Geographic Nicotine Customization as Offensive Strategy
What BAT disclosed
Modern Oral revenue increased 48% in FY2025 . In the U.S., Velo Plus reached the No. 2 position in volume and value within one year of launch .
BAT has submitted a PMTA for its international Velo variant and is awaiting FDA review .
In Europe, Velo Shift was introduced as a premium line emphasizing comfort pouch design and sensory layering.
2Firsts Analysis
The portfolio details indicate a shift away from standardized global SKUs toward geographic product architecture.
Nicotine consumption cultures differ structurally:
● U.S. consumers have a historical preference for moist snuff and dip, typically favoring higher moisture and stronger impact.
● Nordic and broader European consumers are accustomed to traditional snus, valuing discretion and pouch comfort.
The differentiation between Velo Plus/Velo Max (higher moisture, stronger positioning in the U.S.) and Velo Shift (comfort and sensory refinement in Europe) suggests deliberate product re-engineering rather than superficial flavor extension.
Modern Oral, in 2Firsts’ assessment, functions as BAT’s primary offensive growth engine — combining margin expansion with localized relevance.
3. Heated Products: Form Factor Convergence and Pain-Point Resolution
What BAT disclosed
BAT acknowledged competitive pressure in Heated Tobacco during 2025 and introduced glo HiLo, featuring:
● A two-piece device format
● Dual heating with TurboStart™
● A no-cleaning design
● Connectivity integration
Early trial-to-retention rates are around 50% in launch markets .
2Firsts Analysis
The shift from an all-in-one format to a two-piece device marks a significant departure from BAT’s prior design philosophy.
This change likely reflects three strategic recalibrations:
1. Premium segment users value device ritual and separation of charger and holder.
2. Competing premium ecosystems have set format expectations.
3. Cleaning inconvenience remains a key friction point in heated adoption.
The introduction of a no-cleaning system signals a generational heating redesign — potentially narrowing differentiation gaps with premium competitors.
In this category, glo appears positioned as a corrective strategy: reshaping product architecture to address previous structural disadvantages.
4. Combustibles: Laddering as Value Retention Mechanism
What BAT disclosed
U.S. combustibles declined approximately 7–8% in recent years .
BAT described its “laddering” approach, offering migration pathways from:
● Newport (premium)
● Pall Mall Select (mid-tier)
● Doral (deep discount)
Management stated Doral expansion is “not for the sake of market share” but for value protection .
2Firsts Analysis
This structure acknowledges structural downtrading under macroeconomic pressure.
Rather than defending premium pricing rigidly, BAT is creating internal downgrade pathways to reduce leakage to competitors.
Combustibles, in this configuration, serve primarily as a capital base to fund smokeless innovation.
Portfolio-Level Assessment
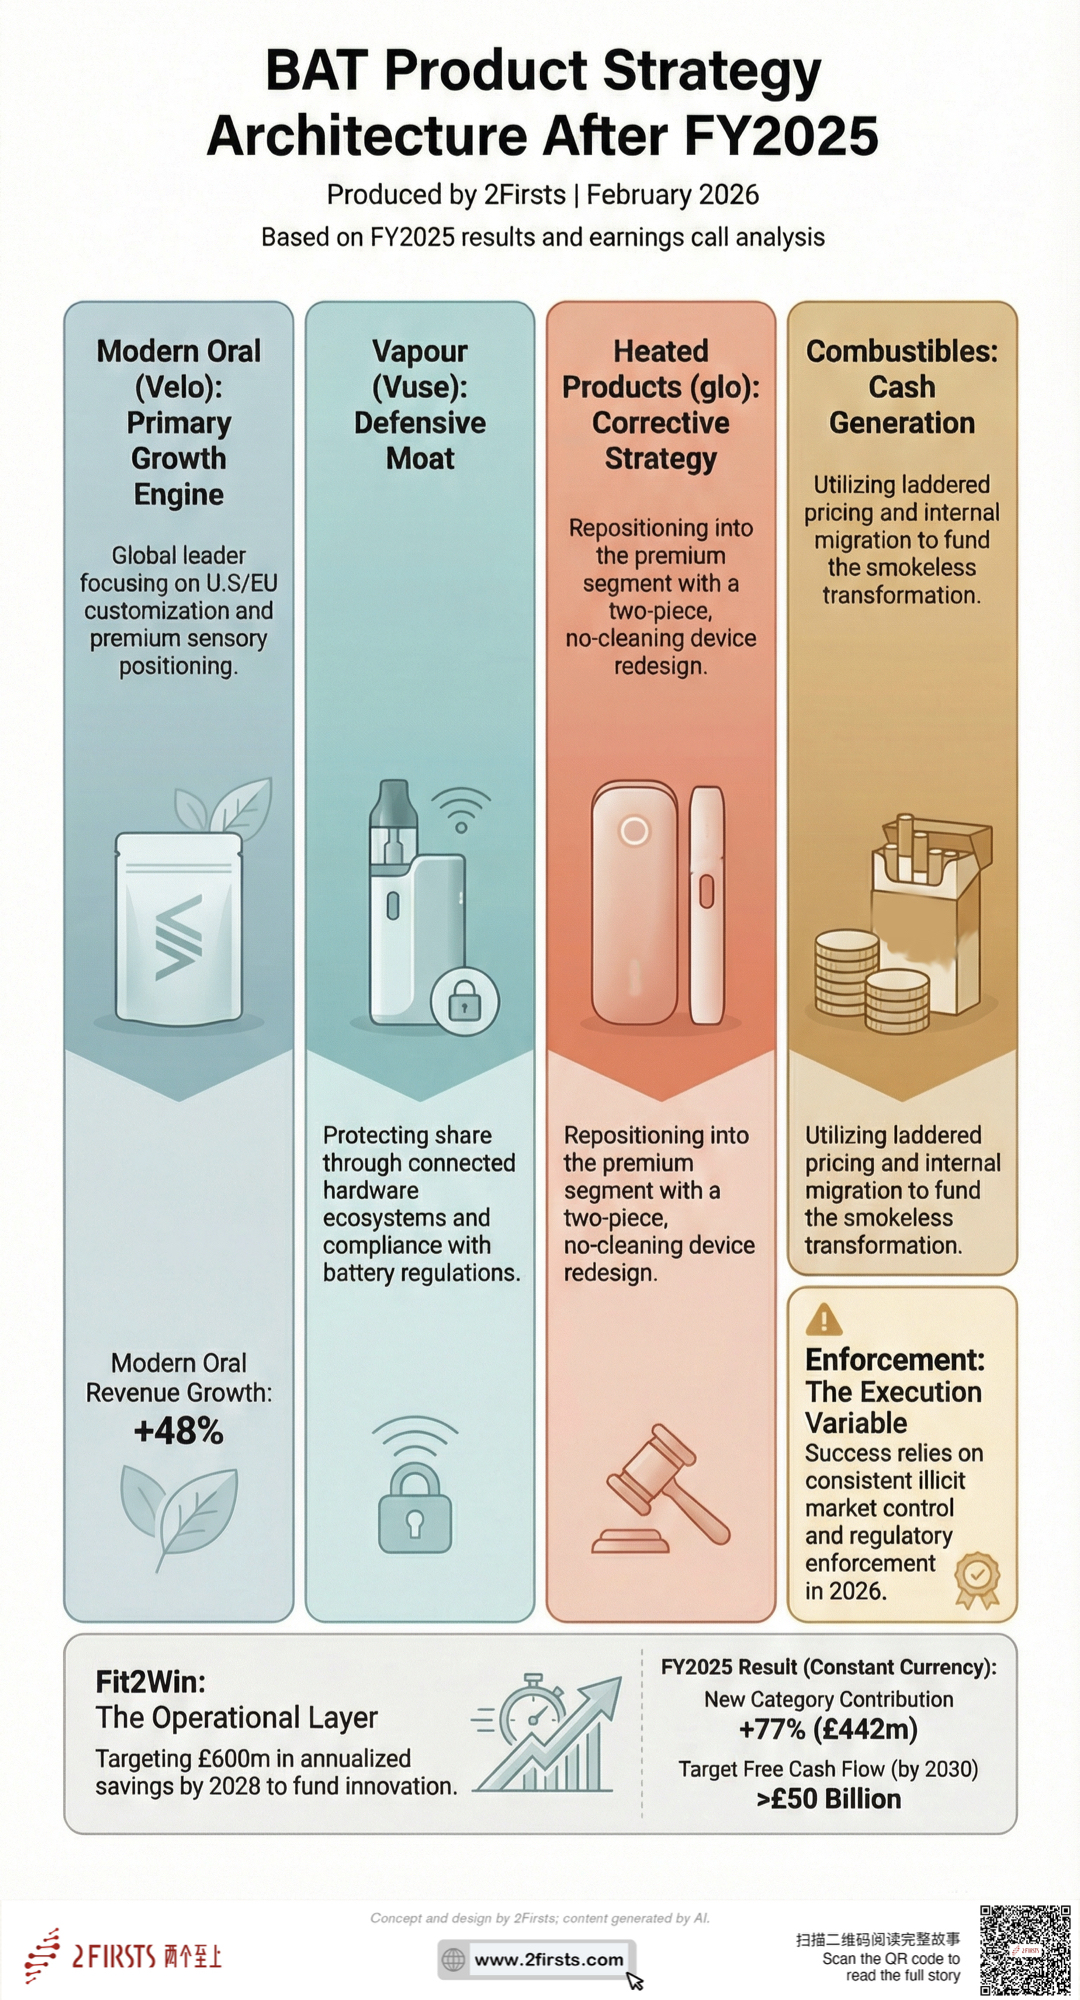
Across categories, BAT’s architecture appears increasingly role-defined:
● Velo — growth and margin expansion
● Vuse — ecosystem defense and regulatory moat
● glo — premium repositioning and structural repair
● Combustibles — value defense and cash generation
Management indicated that 2026 will involve concentrated reinvestment and may be non-linear in profit progression .
From 2Firsts’ analysis, BAT’s FY2025 disclosures suggest a transition from expansionary scaling toward competitive entrenchment.
Execution Risk: The Enforcement Dependency
From 2Firsts’ assessment, BAT’s premium-led, compliance-heavy strategy rests on a critical prerequisite: sustained regulatory enforcement against low-cost illicit products.
Connected devices, removable batteries, and complex hardware architecture increase R&D and production costs. These investments assume that regulators will meaningfully restrict the “simple, low-cost” segment of the market.
If enforcement momentum weakens or proves inconsistent across jurisdictions, pricing pressure from illicit competitors — operating with structurally lower compliance costs — could dilute the return profile of these innovations.
This does not invalidate the strategy. However, it suggests that execution risk lies less in product development and more in regulatory consistency.
BAT’s FY2025 disclosures indicate that the company is attempting to convert product innovation into structural competitive advantage through ecosystem integration, geographic customization, portfolio tiering, and pricing architecture.
Whether that architecture translates into sustained algorithm delivery will depend not only on launch cadence, but on enforcement credibility in key markets.
Further analysis to follow from 2Firsts.
(Cover image:Velo display area at Stockholm Airport |Photo: 2Firsts)