Philip Morris Lowers Profit Outlook as Zyn Faces Competition and FDA Delays

PMI
Jun.02
 Philip Morris Lowers Profit Outlook as Zyn Faces Competition and FDA Delays
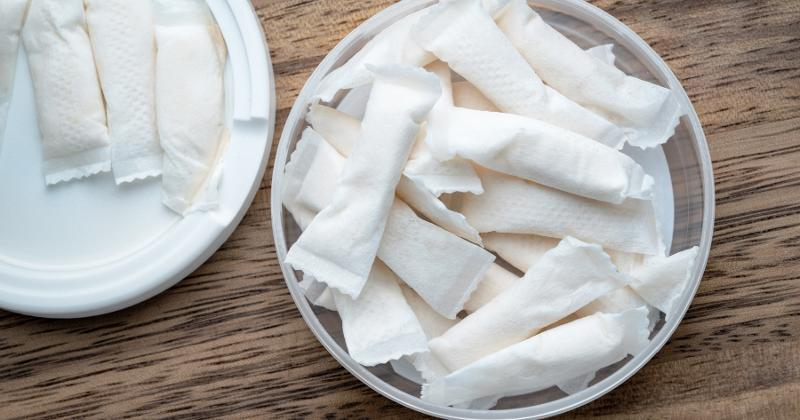
According to Reuters, Philip Morris International (PMI) lowered its 2026 adjusted earnings-per-share forecast amid regulatory uncertainty around Zyn nicotine pouches, rising competition and shipment pressure in the U.S. market.

Key Points

  • PMI lowers full-year EPS guidance;
  • Zyn faces FDA regulatory uncertainty;
  • U.S. Zyn shipments fall 23.5%;
  • VELO competition continues rising.

2Firsts,

June 2, 2026 

According to Reuters, Philip Morris International (PMI) cut its 2026 profit forecast amid regulatory uncertainty over Zyn nicotine pouches and rising competition across tobacco products.  

PMI now expects full-year adjusted earnings per share of $8.36 to $8.51, down from its previous forecast range of $8.38 to $8.53. Reuters, citing LSEG data, said the midpoint remains about four cents above analysts’ expectations.  

The report said PMI is accelerating its shift away from conventional cigarettes toward smoke-free products, but its Zyn nicotine pouch business is facing regulatory delays and stronger competition in the U.S. market.

PMI Chief Financial Officer Emmanuel Babeau said a complex regulatory environment continues to slow innovation and the transition of adult smokers to smoke-free products.

Reuters previously reported that popular nicotine pouch products, including new variants such as Zyn Ultra, have not yet been cleared for sale in the United States by the Food and Drug Administration (FDA). The agency remains cautious about risks to potential new users, including children and teenagers.  

Babeau said PMI aims to maintain Zyn’s premium positioning despite increasingly aggressive pricing from competitors.

The report said PMI is facing competition from products including British American Tobacco’s VELO. Jefferies analyst Andrei Andon-Ionita said pressure on Zyn volumes suggests continued momentum loss, contrary to consensus expectations for brand reacceleration in the second half of the year.

He said VELO is likely to benefit from Zyn’s declines.

Financially, PMI reported first-quarter revenue of $10.15 billion, above market expectations of $9.91 billion. Adjusted earnings per share reached $1.96, also above expectations of $1.83.  

However, U.S. Zyn shipments fell 23.5%. The company attributed the decline mainly to distributor and retailer inventory adjustments rather than weaker consumer demand.  

At the same time, shipments for PMI’s international smoke-free unit rose 11.9%, indicating continued growth outside the U.S. market.  

The company also said its full-year forecast includes a small impact from the Middle East conflict, though it does not expect a prolonged effect.

Despite the profit forecast cut, PMI shares rose about 6% after the results, supported by stronger-than-expected first-quarter earnings and growth in its international smoke-free business.  

Industry observers said PMI’s updated guidance reflects a more competitive nicotine pouch market: Zyn remains central to the company’s smoke-free strategy, but FDA review timelines, rival pricing and channel inventory adjustments are increasingly shaping its U.S. growth outlook.

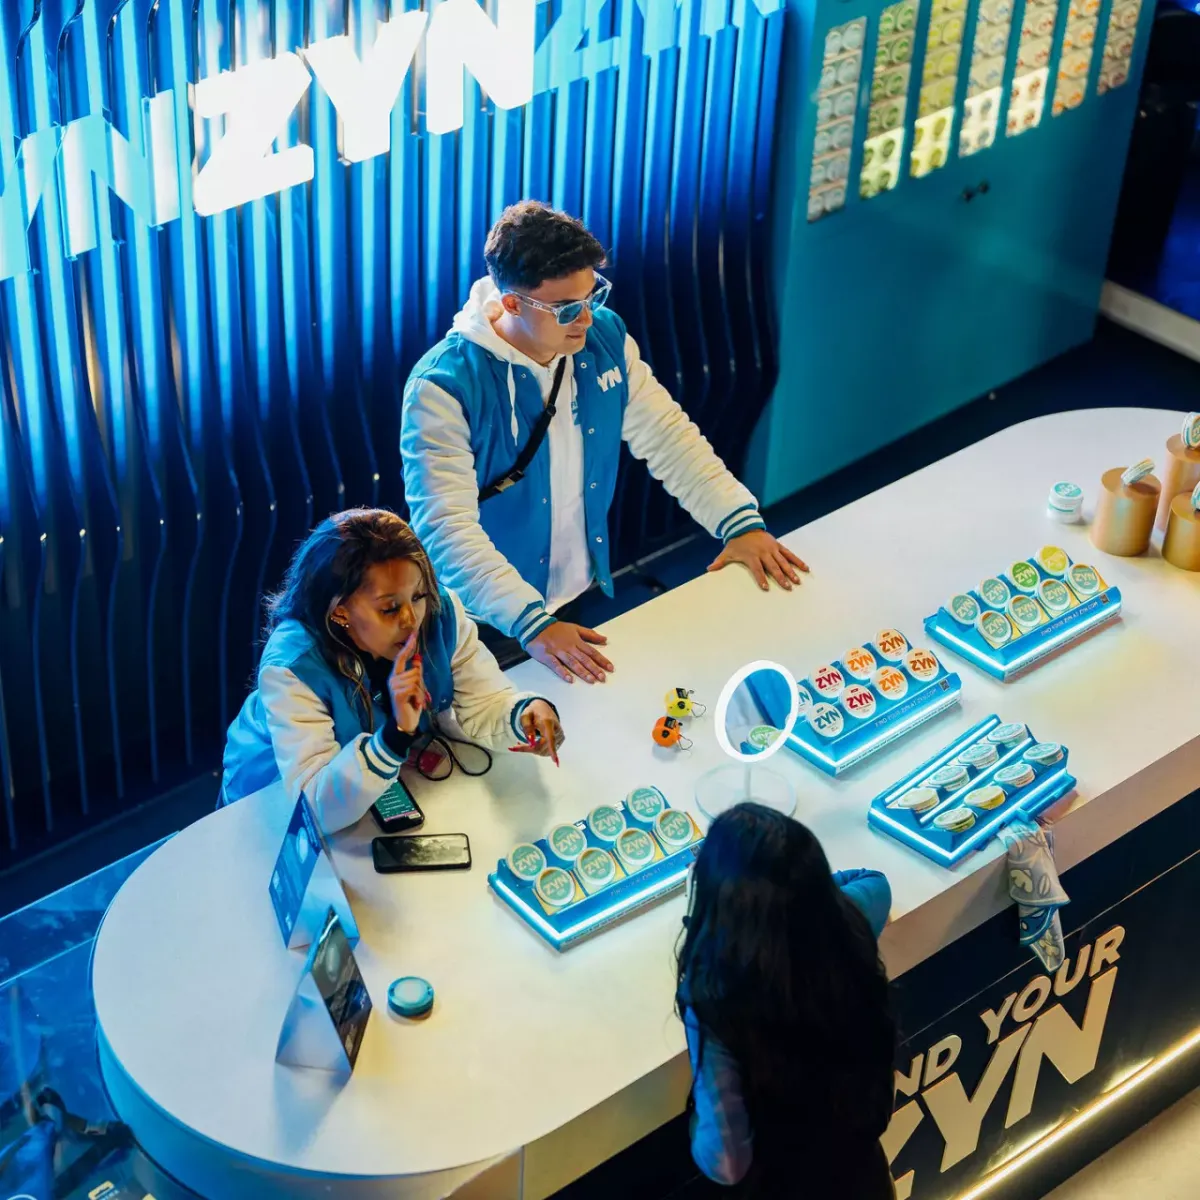
(Cover Image:ZYN)
PMI's IQOS Extends ZAMNA Electronic-Music Partnership to Spain as Vogue España Publishes Branded Content
Philip Morris International's IQOS has extended its partnership with electronic-music event brand ZAMNA to Spain, setting up a House of IQOS at ZAMNA Madrid. Vogue España and Time Out Madrid subsequently published branded content clearly labeled as collaborations with IQOS. PMI has also expanded its company-owned IQOS boutique network in Spain to seven cities this year. The company says IQOS's adjusted heated-tobacco market share in Europe reached 12.6% in the first quarter of 2026, with Spain among its stronger-performing European markets.
Sep.20
Cochrane 2026 Update Adds Nine Trials, Keeps High-Certainty Finding That Nicotine E-Cigarettes Improve Quit Rates Over NRT
Cochrane’s 2026 update of its living review on electronic cigarettes for smoking cessation included 80 randomized controlled trials involving 29,861 adult smokers, with nine trials added in this update. The review retained its high-certainty conclusion that nicotine e-cigarettes increase smoking cessation rates compared with nicotine replacement therapy. In absolute terms, about 10 in 100 people using nicotine e-cigarettes may quit smoking for at least six months, compared with about 6 in 100 using NRT. The review found no clear difference in serious adverse event rates between the two groups, while longer-term safety and the relative effectiveness of newer device types remain less certain.
Sep.07
Couche-Tard Posts Double-Digit U.S. Same-Store Growth in Other Nicotine Products, Led by Pouches
Alimentation Couche-Tard said U.S. same-store sales in its “other nicotine products” category grew at a double-digit rate in the first quarter of fiscal 2027, led by nicotine pouches, while overall U.S. same-store merchandise revenues increased 1.7%. The company also said its Canadian nicotine business continued to face regulatory pressure and illicit-market headwinds. The U.S. performance coincides with Couche-Tard's participation in efforts to reopen Canadian convenience-store access to authorized nicotine pouches, though the company has not established a direct causal link between the two.
Sep.14
After Apple Business Decline, South Korea’s ITM Semiconductor Expands KT&G Vape Supply Chain as Vape Revenue Rises 24.8%
South Korean electronics component supplier ITM Semiconductor is reshaping its business portfolio after a decline in Apple-related protection circuit business, expanding its supply of vape devices and cartridges to KT&G. According to News1 on August 18, 2026, ITM’s vape-related revenue rose 24.8% year on year to 75.5 billion won in the first half of 2026. The company began mass production of vape devices at its Cikarang, Indonesia facility in January 2026, strengthening export manufacturing capacity. Meanwhile, Samsung-related protection circuit sales continued to grow, providing support during the transition.
Aug.20
Ispire Q4 Revenue Rebounds 33% but Full-Year Sales Still Fall 25% as FY2027 Focus Shifts to Malaysia Manufacturing, ODM, Nicotine Pouches and Age Verification
Ispire Technology reported FY2026 revenue of about $96 million, down 24.7% year over year, as U.S. cannabis-vapor hardware and European e-cigarette sales declined by $17.4 million and $12.7 million, respectively. Fourth-quarter revenue rose 32.5% to $26.7 million, while quarterly gross margin fell to 6.3%. For FY2027, the company is prioritizing Malaysia manufacturing and vapor ODM while continuing to develop nicotine pouches, IKE Tech age-verification technology and G-Mesh licensing. Ispire has not separately disclosed the revenue or profit contribution of those newer businesses.
Regulations
Sep.17 by 2Firsts Perspectives
UK-Listed Consumer Goods Group Supreme Sees Vape Duty as Potential Consolidation Opportunity, Holds FY27 Outlook
UK-listed consumer goods group Supreme plc says it continues to expect FY27 trading to meet market expectations as the Vaping Products Duty takes effect on October 1, while maintaining a comparatively positive view of the new tax and compliance regime. Supreme has said the framework could increase compliance complexity for smaller operators and contribute to market consolidation, while its manufacturing, compliance and distribution scale may allow it to gain share. Its 88Vape brand will retain its value positioning.
Sep.18