Key Points
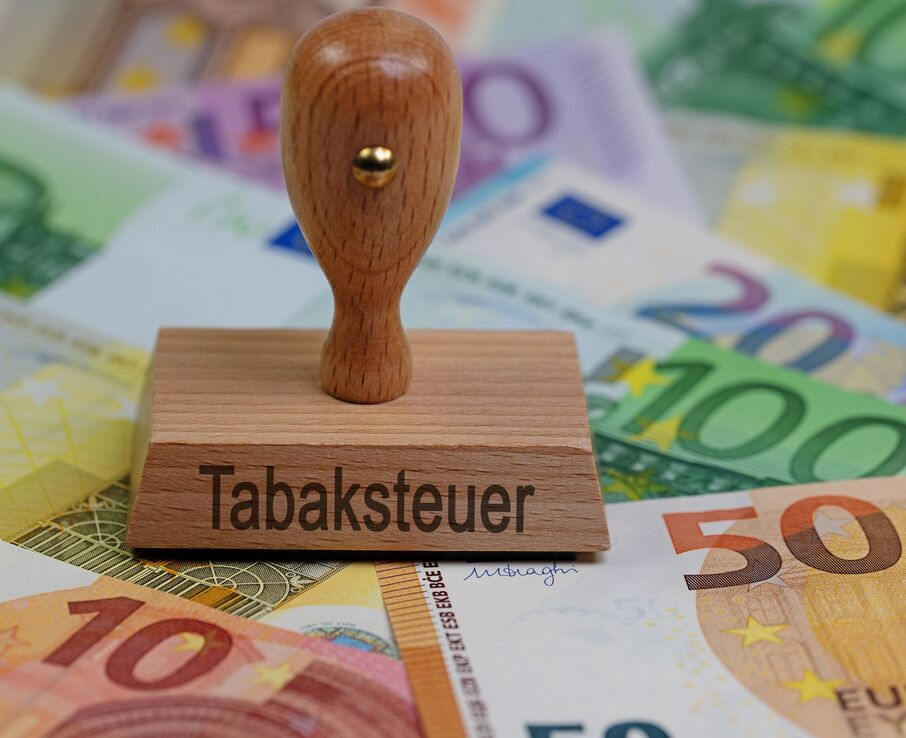
- German total tobacco tax revenue was €9.789 billion in January-August 2026, down 10.8% year over year. The tax category includes cigarettes, fine-cut tobacco, heated tobacco and vaping liquids.
- BVTE, citing federal statistics, said tax-paid cigarette volume fell 12.6% to 40.6 billion sticks, with cigarette tax revenue down 11.3% to €7.42 billion.
- Federal Statistical Office data show full-year 2025 tax-paid cigarette volume rose just 0.2%, while tax-paid tobacco substitutes, including vaping liquids, increased 18.2%.
- The government plans further annual tax increases from 2027 through 2030 and forecasts €756 million in additional revenue in 2027. Parliament will hold a first reading on September 24.
2Firsts
September 23, 2026
According to the German Association of the Tobacco Industry and Novel Products, or BVTE, on September 22, the latest monthly fiscal data from Germany's Federal Ministry of Finance show that total tobacco tax revenue reached €9.789 billion from January through August 2026, down 10.8% from €10.975 billion in the same period last year.
Germany's tobacco tax category covers more than cigarettes. It also includes fine-cut tobacco, heated tobacco and vaping liquids taxed as tobacco substitutes.
August tobacco tax revenue alone was €1.247 billion, down 5.4% year over year.
Germany's 2026 tobacco tax budget estimate is €16.890 billion, compared with €17.632 billion in 2025.
Tax-Paid Cigarette Volume Falls 12.6%
The German Association of the Tobacco Industry and Novel Products, or BVTE, citing German federal statistical data, said tax-paid cigarette volume fell from 46.5 billion sticks in January-August 2025 to 40.6 billion sticks in the same period of 2026, a decline of 12.6%.
Related net cigarette tax revenue fell from about €8.37 billion to €7.42 billion, down 11.3%.
BVTE also said tax-paid fine-cut tobacco volume declined from 16,267 tonnes to 15,395 tonnes, down 5.4%, while related tax revenue fell 4.6% to around €1.5 billion.
Cigarettes remain one of the largest contributors to Germany's tobacco tax base, but the overall revenue figure also includes other traditional tobacco and novel nicotine-product categories.
Tax-Paid Tobacco Substitutes Rose 18.2% in 2025
Federal Statistical Office data for full-year 2025 show that 66.4 billion cigarettes were taxed in Germany, up 0.2% from 2024, while tax-paid fine-cut tobacco volume fell 1.2% to 24,864 tonnes.
Tax-paid tobacco substitutes, including vaping liquids, increased 18.2% over the same period.
The 10.8% decline in total tobacco tax revenue through August 2026 therefore does not mean that every taxable product category fell at the same rate. BVTE's latest product-level figures primarily show weakness in cigarettes and fine-cut tobacco.
Year-to-Date Revenue Decline Narrows From July
Finance Ministry data showed tobacco tax revenue of €8.542 billion through July, down 11.5% year over year.
By the end of August, the year-over-year decline had narrowed to 10.8%.
BVTE is citing lower tax receipts and tax-paid cigarette volumes in arguing against further increases.
BVTE Managing Director Jan Mücke said larger tax increases may fail to generate the revenue expected by the government when legal-market sales and tax receipts are already below year-earlier levels.
The Finance Ministry's monthly report does not assign a single cause to the decline in tobacco tax revenue.
Some Tobacco and Vape Taxes Already Rose in 2026
Germany's existing tax framework scheduled phased tobacco tax changes from 2022 through 2026.
From January 1, 2026, tax rates increased further for categories including cigarettes, fine-cut tobacco and vaping liquids.
The duty on vaping liquids and other tobacco substitutes rose from €0.26 per ml in 2025 to €0.32 per ml in 2026.
BVTE is using this year's tax and volume figures to oppose another round of larger increases beginning in 2027.
Government Forecasts €756 Million in Additional Revenue in 2027
The German government has proposed further annual increases from 2027 through 2030 under amendments to the Tobacco Tax Act.
The bill submitted to the Bundestag forecasts €756 million in additional tax revenue in 2027, rising to about €3.589 billion in additional annual revenue by 2030.
Under the current proposal, by 2030:
- the average cigarette tax burden would rise to 28.77 euro cents per stick;
- heated tobacco would rise to 23.12 cents per stick;
- vaping liquids and other tobacco substitutes would be taxed at €0.36 per ml;
- and fine-cut tobacco would be taxed at €210.51 per kg.
The government says the reform would support federal budget consolidation while also contributing to public-health goals, including lower smoking rates among adults and young people.
BVTE Warns of Cross-Border and Illicit Purchasing
BVTE argues that higher taxes could push consumers toward cross-border purchases or illicit supply and further reduce sales through Germany's legal market.
Germany's Finance Ministry takes a different view.
In its explanation of the tax proposal, the ministry says there is currently no independent empirical evidence showing that higher tobacco taxes necessarily lead to a larger illicit market.
The government also says tax increases in neighboring countries, together with broader EU tax changes, mean it does not expect a significant rise in cross-border purchasing.
BVTE has additionally said that current coalition discussions could involve higher cigarette taxes than those in the original bill and could lift expected additional 2027 revenue to around €1.5 billion.
The government bill currently scheduled for its first Bundestag reading still uses €756 million as the official 2027 additional-revenue estimate.
Bundestag First Reading Set for September 24
Germany's Bundestag is scheduled to hold a first reading of the Tobacco Tax Act amendment at 10:15 p.m. on September 24.
The debate is scheduled to last about 20 minutes, after which the bill is expected to be referred to parliamentary committees, with the Finance Committee serving as the lead committee.
If approved in its current form, the next round of tax increases would begin on January 1, 2027 and continue through 2030.
Follow 2Firsts for timely updates on global tobacco and nicotine taxation, market data and regulatory developments.
Cover Image: BVTE
Disclaimer
This article is provided solely for professional research, industry discussion, and informational purposes. Any references to brands, companies, products, technologies, or policies are made for factual reporting and analytical purposes only, and do not constitute endorsement, recommendation, promotion, or advertising by 2Firsts.
Nicotine-containing products, including but not limited to cigarettes, e-cigarettes, heated tobacco products, and nicotine pouches, carry significant health risks. Readers are responsible for complying with all applicable laws and regulations in their respective jurisdictions, including age restrictions and access limitations.
The information contained in this article should not be regarded as investment, legal, medical, regulatory, or commercial advice. While 2Firsts strives to ensure the accuracy and reliability of its content, it does not assume liability for any direct or indirect loss arising from errors, omissions, inaccuracies, or reliance on the information contained herein.
This article is not intended for individuals below the legal age for accessing tobacco or nicotine-related information in their jurisdiction.
Copyright Notice
This article is either original content produced by 2Firsts or content reproduced, translated, summarized, or adapted from third-party sources with attribution where applicable. The intellectual property rights of the original content remain with 2Firsts or the respective original rights holders.
No individual or organization may copy, reproduce, distribute, republish, modify, translate, or otherwise use this content without prior authorization. Any unauthorized use may result in legal action.
For copyright-related inquiries, corrections, or removal requests, please contact: info@2firsts.com.
AI-Assisted Translation and Editing Notice
Portions of this article may have been translated, edited, or reviewed with the assistance of artificial intelligence tools to improve efficiency and readability. Due to the limitations of AI-assisted translation and editing, discrepancies, omissions, or inaccuracies may exist when compared with the original source.
Where applicable, readers are advised to refer to the original source for the most complete and accurate information. If you identify any errors or believe that any content infringes upon your rights, please contact us at info@2firsts.com, and we will review and address the matter promptly.