KT&G to Enhance Competition in Eurasia with Uzbekistan Expansion.

Jan.14.2025
KT&G to Enhance Competition in Eurasia with Uzbekistan Expansion.
KT&G to establish legal entity in Uzbekistan to enhance competitiveness in Eurasian market, following successful localization efforts.

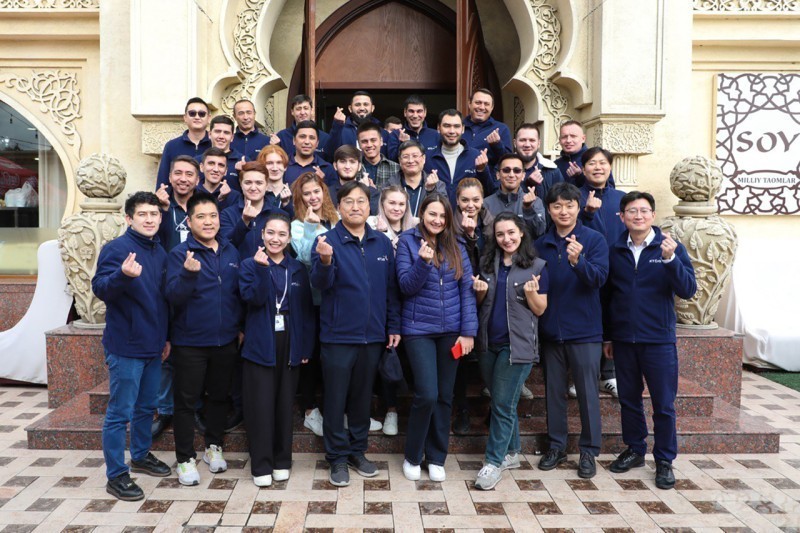
According to a report by N. News on January 13th, Korean Tobacco (referred to as "KT&G" hereafter) announced plans to establish a corporate entity in Uzbekistan, aiming to enhance their competitive edge in the Eurasian region.


Previously, KT&G had established an office in Uzbekistan in 2023 and exported localized products of the ultra-slim cigarette brand "ESSE". In 2024, sales of seven "ESSE" products in Uzbekistan totaled 270 million units, with the best-selling product "Esse Change" accounting for 64% of the exports.


By transforming its office in Uzbekistan into a legal entity, KT&G plans to enhance its long-term competitiveness in the Eurasian region. The company also plans to increase its local workforce by more than fourfold and establish a more comprehensive sales network to strengthen its market position.


On the other hand, KT&G established regional CICs (Corporate Independent Companies) in the Eurasia and Asia-Pacific regions last year. Currently, KT&G operates in 132 countries worldwide with 6 sales corporations and 3 offices. KT&G stated that it will continue to strengthen its direct business system to enhance profitability.


A representative from KT&G stated that establishing a legal entity in Uzbekistan is part of their continued goal to become a "global top-tier" company, following the establishment of a legal entity in Kazakhstan in 2023. This move is also part of their investment and innovation strategy. KT&G plans to drive global business growth by strengthening their local business systems in the future.


We welcome news tips, article submissions, interview requests, or comments on this piece.

Please contact us at info@2firsts.com, or reach out to Alan Zhao, CEO of 2Firsts, on LinkedIn


Notice

1.  This article is intended solely for professional research purposes related to industry, technology, and policy. Any references to brands or products are made purely for objective description and do not constitute any form of endorsement, recommendation, or promotion by 2Firsts.

2.  The use of nicotine-containing products — including, but not limited to, cigarettes, e-cigarettes, nicotine pouchand heated tobacco products — carries significant health risks. Users are responsible for complying with all applicable laws and regulations in their respective jurisdictions.

3.  This article is not intended to serve as the basis for any investment decisions or financial advice. 2Firsts assumes no direct or indirect liability for any inaccuracies or errors in the content.

4.  Access to this article is strictly prohibited for individuals below the legal age in their jurisdiction.


Copyright


This article is either an original work created by 2Firsts or a reproduction from third-party sources with proper attribution. All copyrights and usage rights belong to 2Firsts or the original content provider. Unauthorized reproduction, distribution, or any other form of unauthorized use by any individual or organization is strictly prohibited. Violators will be held legally accountable.

For copyright-related inquiries, please contact: info@2firsts.com


AI Assistance Disclaimer


This article may have been enhanced using AI tools to improve translation and editorial efficiency. However, due to technical limitations, inaccuracies may occur. Readers are encouraged to refer to the cited sources for the most accurate information.

We welcome any corrections or feedback. Please contact us at: info@2firsts.com
2Firsts First Look|China to End VAT Export Rebates on Vape Devices and Nicotine in April 2027, Following Earlier Removal for HTP Devices and Nicotine Vapes
China's Ministry of Finance and State Taxation Administration announced on October 12, 2026, that value-added tax (VAT) export rebates for vape devices, nicotine and its salts, and certain non-combustible inhalation products will be eliminated from April 1, 2027. The measure adds four tobacco- and nicotine-related customs codes, including 8543400010, which covers vape devices and qualifying empty pods. China previously eliminated rebates for nicotine-containing vaping products and devices under code 8543400090 in April 2026. According to industry classification information held by 2Firsts, the latter currently corresponds to heated tobacco devices. Export excise tax refund and exemption arrangements will remain unchanged.
Special Report
Oct.12
JUUL Purchasers Ask Ninth Circuit to Preserve Antitrust Classes in Case Over Altria’s $12.8 Billion Investment
Private antitrust litigation stemming from Altria's 2018 $12.8 billion investment for a 35% economic interest in JUUL is advancing before the U.S. Court of Appeals for the Ninth Circuit. Direct purchasers, indirect purchasers and indirect resellers of JUUL products filed answering briefs this week seeking to preserve class certifications granted by a California federal court in February. Altria and JUUL argue that individual consumers and large distributors differ too much in purchasing terms to remain in a single direct-purchaser class, while a separate dispute concerns whether California antitrust law can apply to indirect purchasers across 27 jurisdictions. A September trial has been put on hold during the appeal.
Sep.23
German Bundestag Passes Tobacco Tax Hikes: Vape Liquid Duty to Reach €0.44/ml, Heated Tobacco Taxes to Rise and Cigarettes Seen Near €12 a Pack
Germany's Bundestag passed amendments to the Tobacco Tax Act on October 15, 2026, setting out annual excise tax increases from 2027 through 2030 for e-cigarette liquids, heated tobacco, cigarettes and other tobacco products. Under the Finance Committee's amended bill, duty on qualifying e-liquids will rise from €0.32/ml in 2026 to €0.44/ml in 2030, an increase of 37.5%. Heated tobacco will retain its tax calculation based on 80% of the corresponding cigarette excise duty. The average price of a 20-cigarette pack is projected to approach €12 by 2030, with some brands potentially reaching €14. The legislation is projected to generate approximately €11.8 billion in additional tax revenue over four years and remains subject to further legislative procedures.
Regulations
Oct.19
Italy Proposes Earlier Vape and HTP Tax Hikes, New Rules for E-Liquid Pricing, Exclusive Deals and Distribution
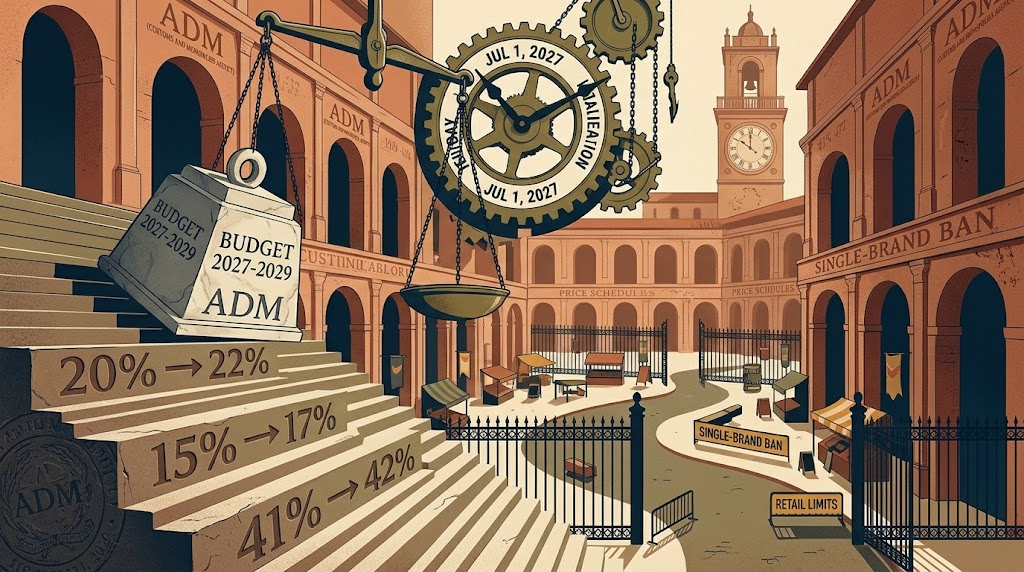
Italy's proposed 2027–2029 budget would bring forward scheduled tax increases for e-cigarette liquids and heated tobacco products from January 1, 2028, to July 1, 2027. The consumption tax coefficient for nicotine-containing e-liquids would rise from 20% to 22%, that for nicotine-free liquids and applicable flavorings from 15% to 17%, and the heated-tobacco coefficient from 41% to 42%. The bill would also introduce official retail price schedules for e-liquids, restrict exclusive agreements between retailers and suppliers, and limit single-brand-dominated displays, sales incentives and bundled offers. Importing, authorized warehousing and retailer sourcing arrangements would also change. The proposals remain subject to parliamentary approval and subsequent implementing regulations.
Regulations
Nov.04
NAS 2026 | Cliff Douglas: Risk Continuum Should Play a Central Role in Tobacco Policy
Cliff Douglas, a veteran U.S. tobacco-control and public health policy figure, told NAS 2026 that the “continuum of risk” should play a central role in tobacco policy. He called for clearer market pathways, stronger risk communication, differentiated regulation and enforcement, and said possible FDA reforms to PMTA reviews could be a “welcome correction” if they create a more efficient, predictable route for scientifically substantiated lower-risk products. Read 2Firsts’ on-site coverage.
Sep.26
South Korea Constitutional Court Upholds Volume-Based E-Liquid Tax, With Challenged Rates at KRW 370 and KRW 628 per Milliliter
South Korea's Constitutional Court has upheld fixed taxes on nicotine-containing e-cigarette liquids based on solution volume, ruling that challenged provisions imposing KRW 370 per milliliter in individual consumption tax and KRW 628 per milliliter in tobacco consumption tax do not violate the Constitution. The cases stemmed from historical disputes involving importers that reported nicotine as being extracted from tobacco stems rather than leaves. South Korea has since broadened its tobacco definition to include synthetic nicotine, while current tax laws provide reduced rates for certain products not derived from tobacco.
Sep.18