RLX Technology Reports 2022 Fiscal Year Financial Performance

Mar.10.2023
RLX Technology Reports 2022 Fiscal Year Financial Performance
RLX Technology released unaudited financial results showing a year-on-year decline in revenue and profit for 2022.

On March 10th, RLX Technology, also known as Yuè Kè, announced its unaudited financial results for the year ended December 31st, 2022, and its Q4 financial results on the NASDAQ website. The company's consolidated financial report showed that its net revenue for the full year of 2022 was RMB 5.33 billion, a 37.41% decrease compared to RMB 8.52 billion in 2021. Its net profit for 2022 was RMB 1.409 billion, compared to RMB 2.028 billion in 2021.


Financial summary for the fourth quarter of 2022.


The net revenue for the fiscal year 2022 was 340 million yuan (49.3 million USD), which is a decrease of 82.14% compared to the same period in 2021, where it was 1.9044 billion yuan. The gross profit margin for the year was 43.6%, compared to last year's 40.2%. The net loss under US GAAP was 225.1 million yuan (32.6 million USD), while last year's net profit under US GAAP was 494.4 million yuan. The non-US GAAP net income for the year was 249.7 million yuan (36.2 million USD), compared to last year's 536.5 million yuan. This is a summary of the financial results for the fiscal year 2022.


In the fiscal year of 2022, the net revenue for the company was 53.328 billion Yuan (7.732 billion USD), a decrease from the previous year's revenue of 85.210 billion Yuan. The gross profit margin for 2022 was 43.2%, slightly higher than the previous year's margin of 43.1%. Under the Generally Accepted Accounting Principles in the United States, the net revenue for 2022 was 14.087 billion Yuan (2.042 billion USD), down from the previous year's revenue of 20.281 billion Yuan. The non-US GAAP net revenue for 2022 was 15.749 billion Yuan (2.283 billion USD), a decrease from the previous year's revenue of 22.515 billion Yuan.


References:


RLX Technology has released its financial results for the fourth quarter and fiscal year 2022, which have not been audited.


Disclaimer

This article is provided solely for professional research, industry discussion, and informational purposes. Any references to brands, companies, products, technologies, or policies are made for factual reporting and analytical purposes only, and do not constitute endorsement, recommendation, promotion, or advertising by 2Firsts.

Nicotine-containing products, including but not limited to cigarettes, e-cigarettes, heated tobacco products, and nicotine pouches, carry significant health risks. Readers are responsible for complying with all applicable laws and regulations in their respective jurisdictions, including age restrictions and access limitations.

The information contained in this article should not be regarded as investment, legal, medical, regulatory, or commercial advice. While 2Firsts strives to ensure the accuracy and reliability of its content, it does not assume liability for any direct or indirect loss arising from errors, omissions, inaccuracies, or reliance on the information contained herein.

This article is not intended for individuals below the legal age for accessing tobacco or nicotine-related information in their jurisdiction.


Copyright Notice

This article is either original content produced by 2Firsts or content reproduced, translated, summarized, or adapted from third-party sources with attribution where applicable. The intellectual property rights of the original content remain with 2Firsts or the respective original rights holders.

No individual or organization may copy, reproduce, distribute, republish, modify, translate, or otherwise use this content without prior authorization. Any unauthorized use may result in legal action.

For copyright-related inquiries, corrections, or removal requests, please contact: info@2firsts.com.


AI-Assisted Translation and Editing Notice

Portions of this article may have been translated, edited, or reviewed with the assistance of artificial intelligence tools to improve efficiency and readability. Due to the limitations of AI-assisted translation and editing, discrepancies, omissions, or inaccuracies may exist when compared with the original source.

Where applicable, readers are advised to refer to the original source for the most complete and accurate information. If you identify any errors or believe that any content infringes upon your rights, please contact us at info@2firsts.com, and we will review and address the matter promptly.
Italy Proposes Earlier Vape and HTP Tax Hikes, New Rules for E-Liquid Pricing, Exclusive Deals and Distribution
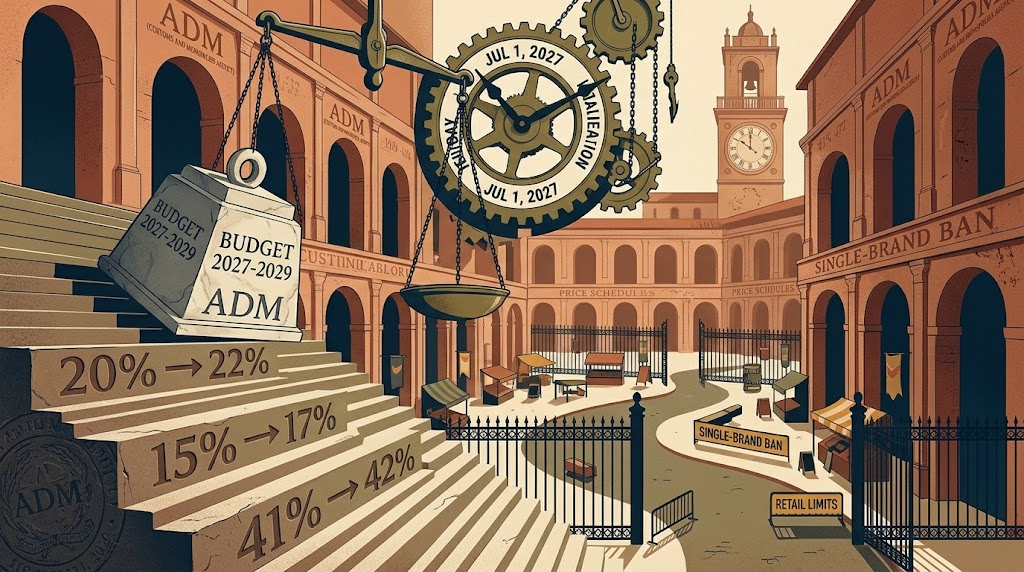
Italy's proposed 2027–2029 budget would bring forward scheduled tax increases for e-cigarette liquids and heated tobacco products from January 1, 2028, to July 1, 2027. The consumption tax coefficient for nicotine-containing e-liquids would rise from 20% to 22%, that for nicotine-free liquids and applicable flavorings from 15% to 17%, and the heated-tobacco coefficient from 41% to 42%. The bill would also introduce official retail price schedules for e-liquids, restrict exclusive agreements between retailers and suppliers, and limit single-brand-dominated displays, sales incentives and bundled offers. Importing, authorized warehousing and retailer sourcing arrangements would also change. The proposals remain subject to parliamentary approval and subsequent implementing regulations.
Regulations
Nov.04
STIIIZY Redesign Fails to Escape PAX Labs Patent Import Ban as Section 337 Case Also Involves China ALD
U.S. Customs and Border Protection ruled that STIIIZY had not shown that the redesigned cannabis-vape products covered by its latest request fall outside an ITC limited exclusion order tied to PAX Labs patents. CBP accepted some of STIIIZY’s claim-construction and non-infringement arguments, but the company did not address two additional claims in the same patent. Earlier STIIIZY redesigned cartridges and certain associated components imported with them had received separate CBP clearance.
Sep.16
Special Report|CrossBar's High-Puff Vapes Draw Attention on Pennsylvania's 163-Product Directory as Link Between Earlier 1.3mL PMTA Filings and New 13mL Products Remains Unclear
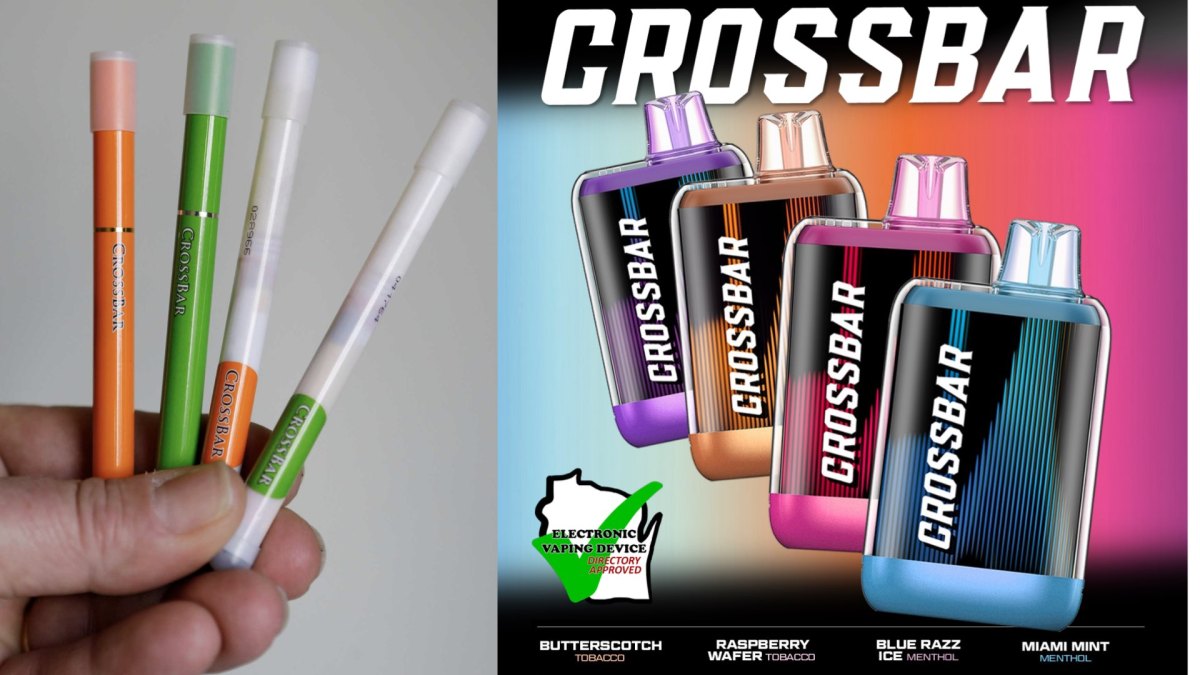
Pennsylvania began enforcing its electronic nicotine delivery system directory restrictions on October 19, 2026. Among 163 product listings recorded before enforcement, four CrossBar 20K disposables stood out with 13mL capacity, advertised puff counts of up to 20,000 and a flattened design distinct from conventional pod systems and compact disposables. Historical records identify earlier 1.3mL CrossBar products associated with Romo LLC, while newer 13mL products appeared in several state directories beginning in 2025 under entities including Blue Nine LLC. PMTA compliance expert Mr. K identified amendments and application ownership transfers as possible regulatory mechanisms, although neither has been confirmed in this case. Separately, Reynolds' $7.5 million acquisition of 16 PACHA products and related assets illustrates the commercial value of products linked to historic PMTA submissions.
Special Report
Oct.22
Arizona Turns to a 50% Retail Vape Tax as Tobacco Tax Revenue Falls 47% From 2008
Arizona's First Things First is pushing for an excise tax equal to 50% of the retail price of vaping products, estimating that the measure could generate about $100 million annually. The agency says its tobacco-tax revenue has fallen 47% from 2008 levels. Arizona has attempted to broaden its nicotine tax base in each of the past two years: a 2025 bill proposed a 50% wholesale-price tax, while a 2026 measure shifted to a 50% retail-price tax covering alternative nicotine products and vapor products. Separately, the state enacted HB 4001 this year to establish a new licensing and sales framework for alternative nicotine products.
Sep.21
New York City Opens Lottery for 55 Vape Retail License Slots Across 23 Community Districts, Including 28 in Brooklyn
New York City's Department of Consumer and Worker Protection (DCWP) opened applications on November 2, 2026, for a lottery covering tobacco and electronic cigarette retail dealer licenses, with a deadline of 5 p.m. New York local time on November 30. According to the city's October 1 notice, 55 electronic cigarette retail license slots are available across 23 community districts, including 28 in Brooklyn, alongside 322 tobacco retail license slots across 41 districts. Businesses must enter the lottery and, if invited, complete licensing requirements within 65 days. New York City continues to restrict e-cigarette retail sales to tobacco-flavored or unflavored products, while city retail licenses do not replace FDA product marketing authorization.
Market
Nov.04
Cochrane 2026 Update Adds Nine Trials, Keeps High-Certainty Finding That Nicotine E-Cigarettes Improve Quit Rates Over NRT
Cochrane’s 2026 update of its living review on electronic cigarettes for smoking cessation included 80 randomized controlled trials involving 29,861 adult smokers, with nine trials added in this update. The review retained its high-certainty conclusion that nicotine e-cigarettes increase smoking cessation rates compared with nicotine replacement therapy. In absolute terms, about 10 in 100 people using nicotine e-cigarettes may quit smoking for at least six months, compared with about 6 in 100 using NRT. The review found no clear difference in serious adverse event rates between the two groups, while longer-term safety and the relative effectiveness of newer device types remain less certain.
Sep.07