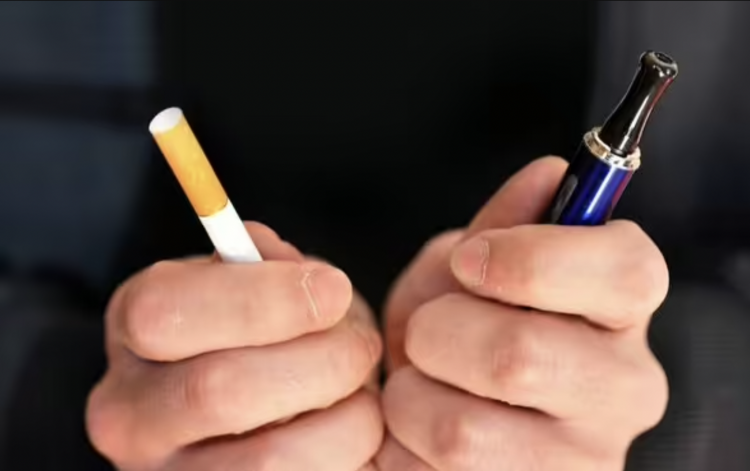
On April 17th, during a meeting in the South Korean National Assembly, the ruling party proposed implementing cigarette-like taxes on heated tobacco products. Two days after the South Korean Finance Minister hinted at a potential parliamentary hearing, on April 19th, the government abandoned its decision to tax heated tobacco products.
In a statement, the Ministry of Finance said, "The government has not currently considered raising tobacco taxes." Previously, the minister's remarks faced strong public opposition.
South Korea's cigarette tax is higher than that of HNB products.
In South Korea, the tax rate for regular cigarettes is higher than the tax rate for HNB pods because the government deems the former more harmful to health.
Each pack of cigarettes is subject to a tax of 3,323 Korean won (equivalent to 17.23 Chinese yuan), which includes:
The tobacco consumption tax is 1007 South Korean won (equivalent to 5.22 Chinese yuan), the education tax is 443 South Korean won (equivalent to 2.29 Chinese yuan), the consumption tax is 594 South Korean won (equivalent to 3.08 Chinese yuan), the value-added tax is 409 South Korean won (equivalent to 2.12 Chinese yuan), the health promotion fee is 841 South Korean won (equivalent to 4.36 Chinese yuan), the waste fee is 24.4 South Korean won (equivalent to 0.12 Chinese yuan), and 5 South Korean won is used to support tobacco farmers (equivalent to 0.026 Chinese yuan).
On the other hand, taxes of 3,004 Korean won (equivalent to 15.63 yuan) are imposed on HNB pods at a tax rate of 90.4% of the standard cigarette product tax rate.
The average price for regular tobacco products and HNB pods is around 4,500 South Korean won (approximately 23.34 Chinese yuan) per unit of consumption.
Cigarette tax reduced, while non-combustible tobacco products taxed increased.
The government's attempt to increase tax rates to boost tax revenue has resulted in public criticism. Data from South Korea's Ministry of Finance show that tax revenue in January and February this year amounted to KRW 54.2 trillion (approximately RMB 282 billion), a decrease of KRW 15.7 trillion (approximately RMB 81.7 billion) compared to the same period last year.
In the past few years, the taxes on tobacco products have also decreased. This is mainly because the sales of regular tobacco products have decreased, rather than an increase in sales of non-combustible tobacco products, which have replaced traditional cigarettes with higher tax rates.
Between 2020 and 2022, the number of tobacco products sold in South Korea increased from 3.59 billion to 3.63 billion, an increase of 1.1%. However, the total tax revenue from all tobacco products decreased from KRW 120 trillion to KRW 118 trillion.
From 2020 to 2022, the sales volume of non-combustible pods increased from 380 million to 540 million, while cigarette sales decreased from 3.2 billion to 3.09 billion packs.
Industry observers have pointed out that the government is unlikely to increase taxes on HNB products, particularly before the general election in April next year.
Related reading:
The price of Korean heating non-burning equipment is twice that of Japan.
South Korea's customs officials have seized counterfeit duty-free electronic cigarettes and e-cigarette liquid, with the estimated amount of tax evasion reaching 500 million South Korean won.
The purchasing managers' index (PMI) for the South Korean market has seen a 163% growth in operating profits, while BAT (presumably referring to the trio of Chinese tech giants Baidu, Alibaba, and Tencent) has experienced a 12% decline.
ELFBAR's Korean distributor has seen an increase in initial orders, with a target of selling 2 million units in South Korea this year.
Reference:
South Korea has retreated from a potential tax increase on heated tobacco products.
Disclaimer
This article is provided solely for professional research, industry discussion, and informational purposes. Any references to brands, companies, products, technologies, or policies are made for factual reporting and analytical purposes only, and do not constitute endorsement, recommendation, promotion, or advertising by 2Firsts.
Nicotine-containing products, including but not limited to cigarettes, e-cigarettes, heated tobacco products, and nicotine pouches, carry significant health risks. Readers are responsible for complying with all applicable laws and regulations in their respective jurisdictions, including age restrictions and access limitations.
The information contained in this article should not be regarded as investment, legal, medical, regulatory, or commercial advice. While 2Firsts strives to ensure the accuracy and reliability of its content, it does not assume liability for any direct or indirect loss arising from errors, omissions, inaccuracies, or reliance on the information contained herein.
This article is not intended for individuals below the legal age for accessing tobacco or nicotine-related information in their jurisdiction.
Copyright Notice
This article is either original content produced by 2Firsts or content reproduced, translated, summarized, or adapted from third-party sources with attribution where applicable. The intellectual property rights of the original content remain with 2Firsts or the respective original rights holders.
No individual or organization may copy, reproduce, distribute, republish, modify, translate, or otherwise use this content without prior authorization. Any unauthorized use may result in legal action.
For copyright-related inquiries, corrections, or removal requests, please contact: info@2firsts.com.
AI-Assisted Translation and Editing Notice
Portions of this article may have been translated, edited, or reviewed with the assistance of artificial intelligence tools to improve efficiency and readability. Due to the limitations of AI-assisted translation and editing, discrepancies, omissions, or inaccuracies may exist when compared with the original source.
Where applicable, readers are advised to refer to the original source for the most complete and accurate information. If you identify any errors or believe that any content infringes upon your rights, please contact us at info@2firsts.com, and we will review and address the matter promptly.