Indian Tobacco Company Reports Strong Q2 2022 Performance

Aug.07.2022
Indian Tobacco Company Reports Strong Q2 2022 Performance
Indian Tobacco Company (ITC) reported strong Q2 performance with revenue and earnings growing 29% and 30.1% respectively.

According to a report from ITC (formerly known as the Indian Tobacco Company Limited, now the Indian Tobacco Company), their cigarette business achieved strong performance in the second quarter of 2022, with segment revenue and segment performance increasing by 29% and 30.1%, respectively, compared to the same period in the previous year.


Photo courtesy of Wirestock.


The Indian Tobacco Company released a statement declaring their commitment to combatting illegal trade. They plan to strengthen their market position through innovation, market segmentation, premiumization, improving product availability, and strict enforcement.


The Indian Tobacco Company has expressed encouragement towards the stable tobacco tax environment and enforcement actions taken by Indian authorities to eliminate illegal trade.


The Indian Tobacco Company stated in a press release that "as demonstrated in the past, stable cigarette taxes, supported by deterrent law enforcement actions, enable the legal cigarette industry to recover trade volumes from illegal trade, generating domestic demand for Indian tobacco, while also alleviating fiscal revenue losses.


The Indian Tobacco Company has stated that it continues to work with government agencies to develop a fair, non-discriminatory, practical, and evidence-based regulatory and taxation policy framework that balances economic benefits and tobacco control objectives. This takes into account India's unique patterns of tobacco consumption, with only a small portion of combustible tobacco production being used to manufacture cigarettes in Indian factories.


Statement:


This article is compiled from third-party information and is intended only for communication and learning within the industry.


This article does not represent the views of 2FIRSTS and 2FIRSTS cannot confirm the truth or accuracy of the content. The translation of this article is only for industry communication and research purposes.


Due to limited translation abilities, the translated article may not fully reflect the original text. Please refer to the original version for accuracy.


2FIRSTS maintains complete alignment with the Chinese government on any domestic, Hong Kong, Macau, Taiwan, or foreign-related statements and positions.


The copyright of compiled information belongs to the original media outlet and author. If there is any infringement, please contact us for removal.


Disclaimer

This article is provided solely for professional research, industry discussion, and informational purposes. Any references to brands, companies, products, technologies, or policies are made for factual reporting and analytical purposes only, and do not constitute endorsement, recommendation, promotion, or advertising by 2Firsts.

Nicotine-containing products, including but not limited to cigarettes, e-cigarettes, heated tobacco products, and nicotine pouches, carry significant health risks. Readers are responsible for complying with all applicable laws and regulations in their respective jurisdictions, including age restrictions and access limitations.

The information contained in this article should not be regarded as investment, legal, medical, regulatory, or commercial advice. While 2Firsts strives to ensure the accuracy and reliability of its content, it does not assume liability for any direct or indirect loss arising from errors, omissions, inaccuracies, or reliance on the information contained herein.

This article is not intended for individuals below the legal age for accessing tobacco or nicotine-related information in their jurisdiction.


Copyright Notice

This article is either original content produced by 2Firsts or content reproduced, translated, summarized, or adapted from third-party sources with attribution where applicable. The intellectual property rights of the original content remain with 2Firsts or the respective original rights holders.

No individual or organization may copy, reproduce, distribute, republish, modify, translate, or otherwise use this content without prior authorization. Any unauthorized use may result in legal action.

For copyright-related inquiries, corrections, or removal requests, please contact: info@2firsts.com.


AI-Assisted Translation and Editing Notice

Portions of this article may have been translated, edited, or reviewed with the assistance of artificial intelligence tools to improve efficiency and readability. Due to the limitations of AI-assisted translation and editing, discrepancies, omissions, or inaccuracies may exist when compared with the original source.

Where applicable, readers are advised to refer to the original source for the most complete and accurate information. If you identify any errors or believe that any content infringes upon your rights, please contact us at info@2firsts.com, and we will review and address the matter promptly.
2Firsts Hosts China Market Forum at InterTabac as Global Industry Attention to China’s Tobacco Sector Deepens
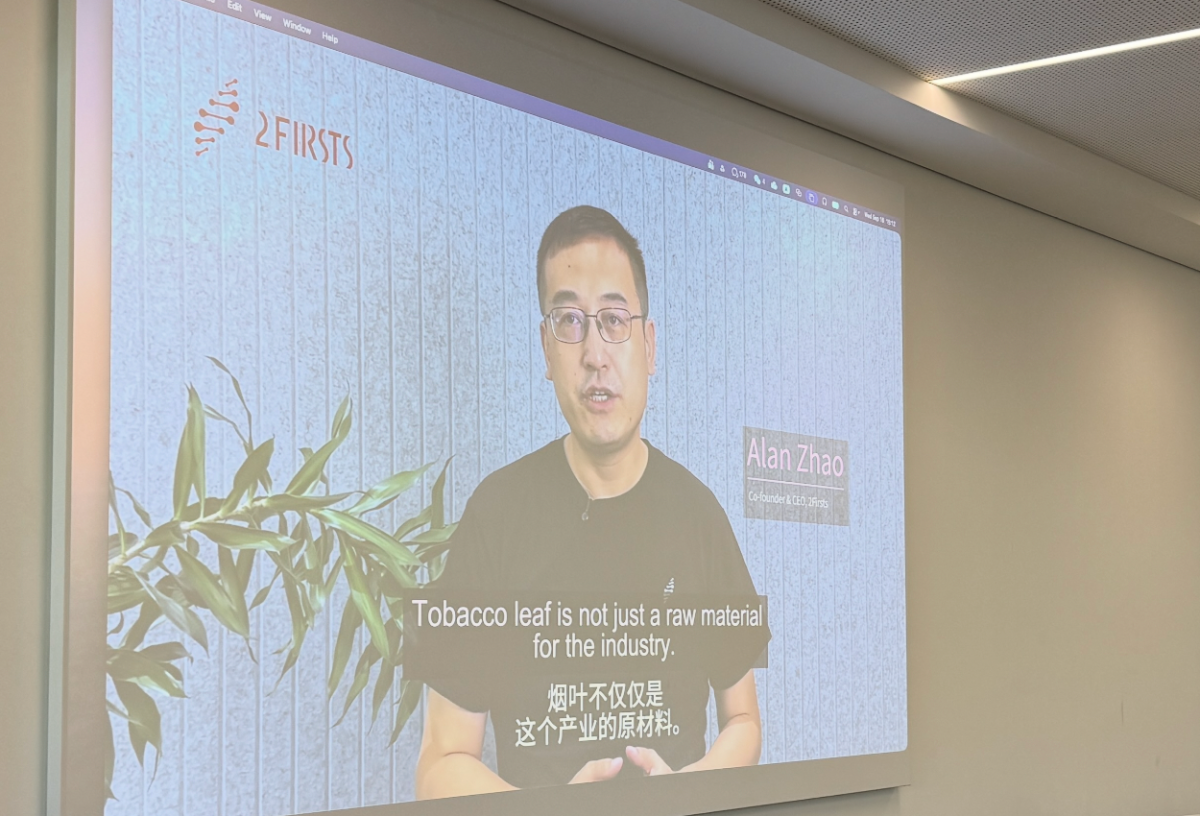
On September 16, 2Firsts hosted a China-focused industry forum during InterTabac in Dortmund, bringing together more than 30 participants from North America, Europe, India, South Korea and other markets. The session covered traditional tobacco, next-generation products, exports, technology, regulation and supply chains, while examining how China’s tobacco sector operates, where its transformation may be heading, and why its growing role matters increasingly to companies across the global tobacco and nicotine industry.
Sep.21
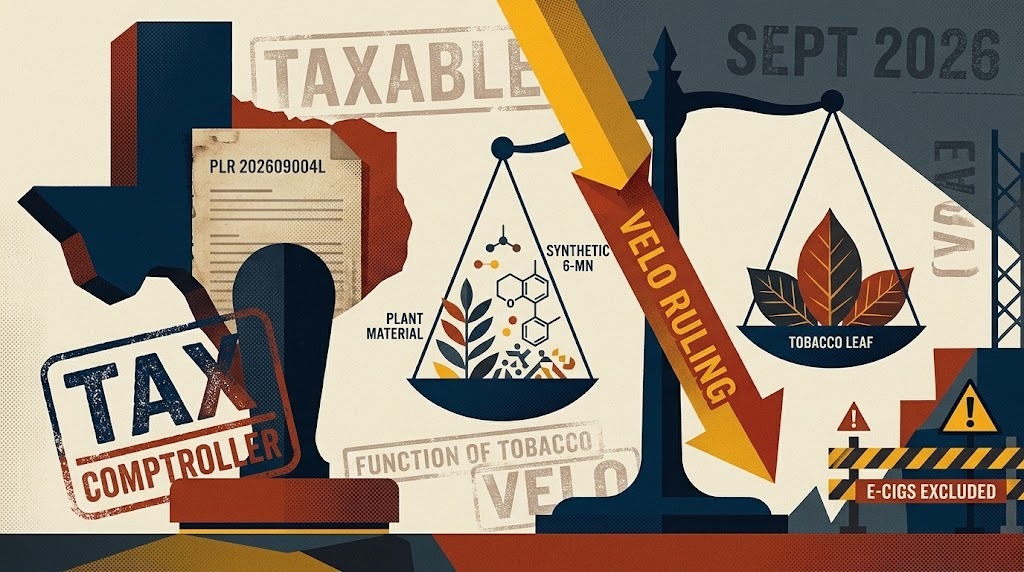
Texas Extends Tobacco Tax Interpretation to a 6-Methylnicotine Product, Citing VELO Ruling
The Texas Comptroller of Public Accounts ruled in September 2026 that a combustible product made with non-tobacco plant material and 6-methylnicotine (6-MN), a synthetic nicotine analog, qualifies as a taxable tobacco product. The applicant said the product contained neither tobacco leaf nor measurable conventional nicotine. The determination applies reasoning from a May Texas Supreme Court decision involving VELO nicotine pouches, finding that the plant material and 6-MN together perform the functions of tobacco in a conventional smoking product. The ruling carries applicable tax, licensing and reporting obligations but is limited to the facts submitted by the taxpayer. It does not establish a blanket tax classification for all 6-MN products or extend the same conclusion to e-cigarettes.
Regulations
Nov.06
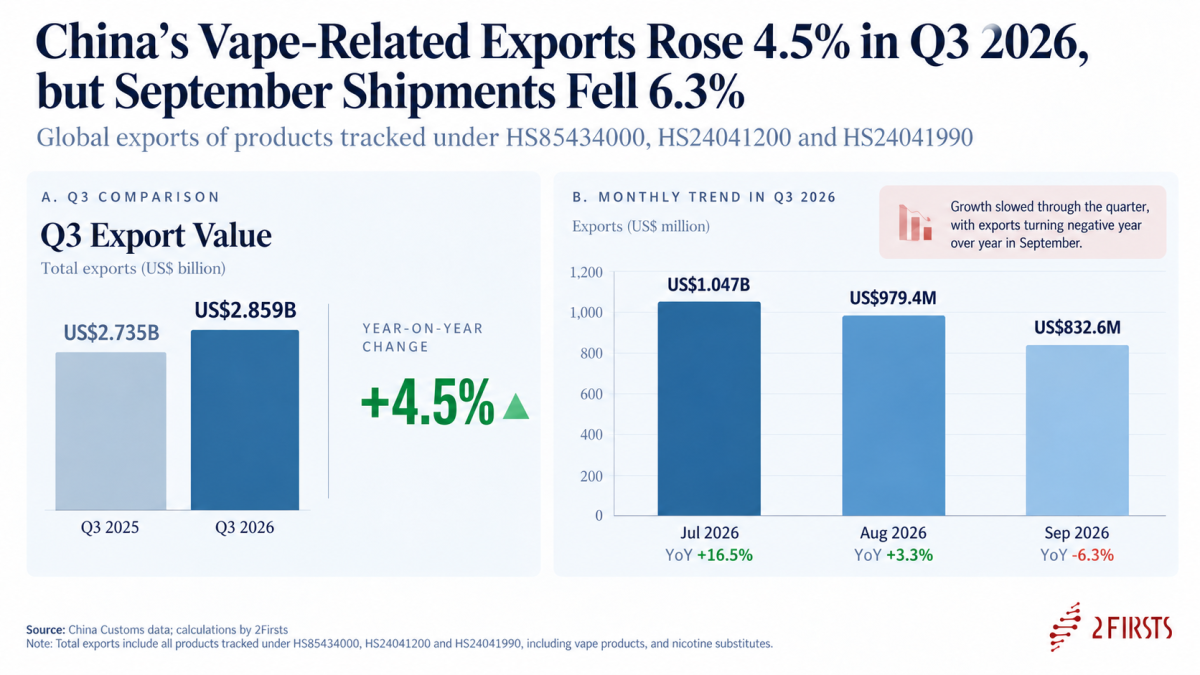
China’s Vape-Related Exports Rose 4.5% in Q3 2026 as 21.6% Growth in Shipments to the UK Offset a Decline in Shipments to the US
China's vape-related exports rose 4.5% year over year to $2.86 billion in the third quarter of 2026, led by stronger shipments to the United Kingdom as exports to the United States declined. UK-bound shipments increased 21.6%, adding $81.9 million, while US exports fell 5.2%, or $53.6 million. Growth weakened through the quarter, with September exports down 6.3% globally and 37.8% to the US. Nicotine-containing vape products accounted for more than 82% of the quarterly net increase, while device exports were nearly flat. Nine-month exports totaled $7.82 billion, up 4.0%.
DATA
Oct.26
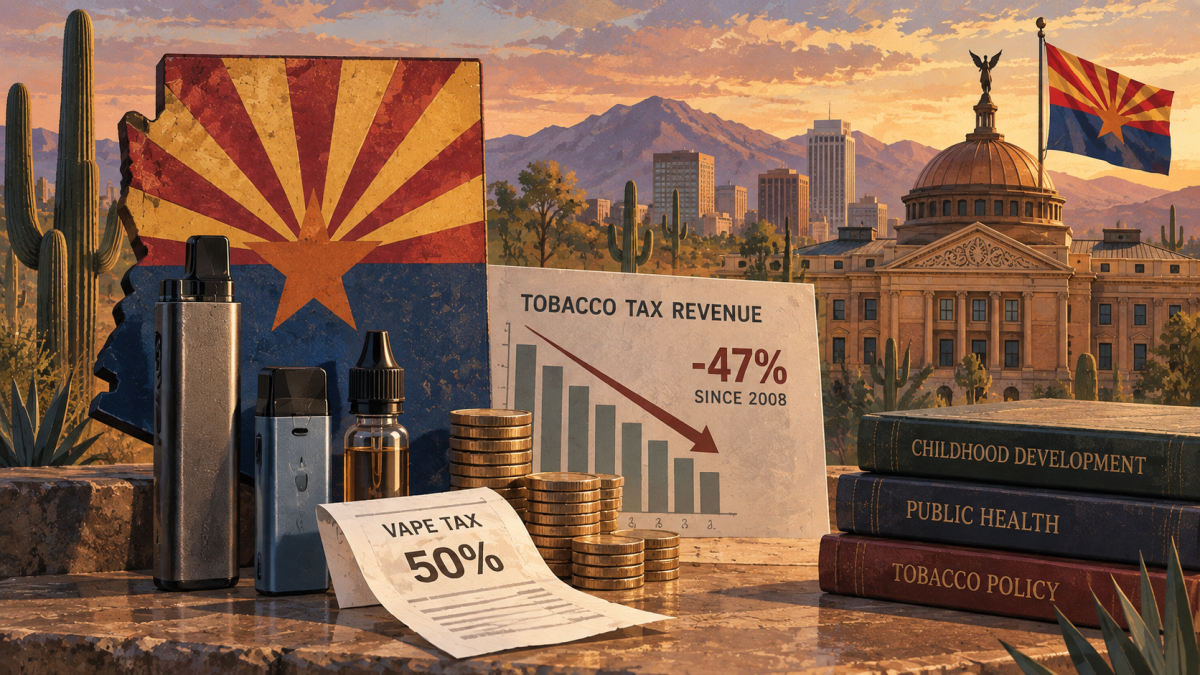
Arizona Turns to a 50% Retail Vape Tax as Tobacco Tax Revenue Falls 47% From 2008
Arizona's First Things First is pushing for an excise tax equal to 50% of the retail price of vaping products, estimating that the measure could generate about $100 million annually. The agency says its tobacco-tax revenue has fallen 47% from 2008 levels. Arizona has attempted to broaden its nicotine tax base in each of the past two years: a 2025 bill proposed a 50% wholesale-price tax, while a 2026 measure shifted to a 50% retail-price tax covering alternative nicotine products and vapor products. Separately, the state enacted HB 4001 this year to establish a new licensing and sales framework for alternative nicotine products.
Sep.21
Canada Health Minister Says She Is Not Considering Looser Nicotine Pouch Retail Rules as PMI-Linked Group Pushes for Wider Access
Canadian Health Minister Marjorie Michel says she is not considering loosening retail restrictions on nicotine pouches. Canada regulates pouches containing 4 mg or less of nicotine per unit as non-prescription nicotine replacement therapy and requires newer NRT formats such as pouches to be sold from behind pharmacy counters. Meanwhile, Unsmoke Canada, linked to Philip Morris International's Canadian business, is pushing to allow pouches in convenience stores and other general retail outlets. Health Canada also acknowledges continued unauthorized sales, while recent research shows rising pouch use among Canadian youth aged 16 to 19.
Sep.24
IVG Parent Secures HMRC Excise Warehouse and Duty Stamp Approvals Ahead of UK Vape Tax
Acme Vape Ltd, the company behind UK vaping brand IVG, has received HM Revenue & Customs approval to operate an excise warehouse for vaping products and participate in the Vaping Duty Stamps Scheme. The UK's Vaping Products Duty will take effect on October 1, 2026, at a flat rate of £2.20 per 10ml of vaping liquid. Acme Vape Ltd says its approved warehouse in Preston will become operational under the new regime on the same date.
Regulations
Sep.18 by 2Firsts Perspectives