KT&G: Tobacco Demand Rebounding, Stronger Shareholder Policies

Business by 2FIRSTS.ai
Jan.19.2024
KT&G: Tobacco Demand Rebounding, Stronger Shareholder Policies
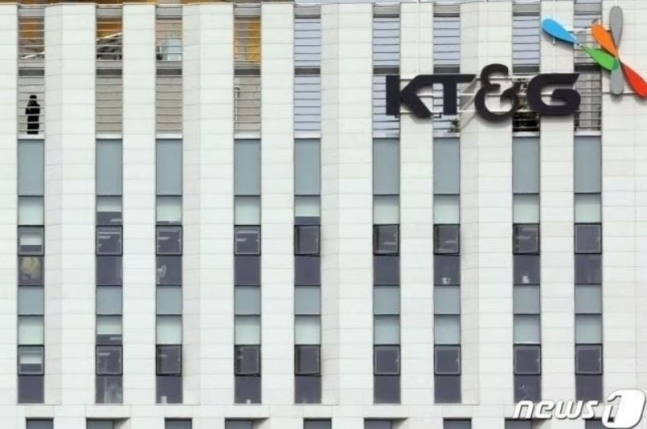
KT&G's overseas tobacco demand rebounds as it strengthens shareholder policies, with sales predicted to grow in Q4.

According to a report from the Chosun Daily on January 19th, Hanwha Investment & Securities conducted an analysis on KT&G, stating that tobacco demand in overseas markets is beginning to recover and its policies towards rewarding shareholders are also strengthening. Hanwha Investment & Securities maintains a "buy" investment position on KT&G, with a target stock price of 110,000 Korean won. As of the previous day, KT&G's trading price had risen to 83,900 Korean won.


According to a report by Han Investment Securities, it is predicted that KT&G's sales in the fourth quarter of last year will increase by 2.8% compared to the previous year, reaching 1.45 trillion South Korean won. However, the operating profit is expected to decline by 3.8% year-on-year, reaching 193.8 billion South Korean won, which is in line with market expectations.


Analyst Zhao Shangxun from Sinhan Investment Securities has indicated that KT&G's three core businesses, namely Next Generation Tobacco Products (NGP), overseas cigarettes, and health food, will drive the company's performance growth. Shangxun suggests that KT&G has been undervalued for a long time, primarily due to its conservative business strategy and weaker cash flow, resulting in a lower return on assets (ROE) compared to global peers.


Zhao Sangxun predicts that once KT&G adopts a more aggressive business strategy, focuses on core growth industries, invests in capital expenditure (CAPEX), and implements shareholder return policies, both its performance and stock price will improve. He also points out that the recent overseas tobacco demand from the Middle East is on the rise, while new markets in Central and South America, as well as the growth of overseas companies, are continuing. At the same time, KT&G's long-term contract with Philip Morris International (PMI) regarding NGP sales will also have a positive impact on the company's development.


Zhao Sangxun also pointed out in the report that KT&G can steadily generate profits independently of the consumer economy or external uncertainties. Due to its relatively low reliance on imported raw materials, KT&G is less affected by fluctuations in food prices. Additionally, its strengthened shareholder feedback policy enhances its investment attractiveness.


We welcome news tips, article submissions, interview requests, or comments on this piece.

Please contact us at info@2firsts.com, or reach out to Alan Zhao, CEO of 2Firsts, on LinkedIn


Notice

1.  This article is intended solely for professional research purposes related to industry, technology, and policy. Any references to brands or products are made purely for objective description and do not constitute any form of endorsement, recommendation, or promotion by 2Firsts.

2.  The use of nicotine-containing products — including, but not limited to, cigarettes, e-cigarettes, nicotine pouchand heated tobacco products — carries significant health risks. Users are responsible for complying with all applicable laws and regulations in their respective jurisdictions.

3.  This article is not intended to serve as the basis for any investment decisions or financial advice. 2Firsts assumes no direct or indirect liability for any inaccuracies or errors in the content.

4.  Access to this article is strictly prohibited for individuals below the legal age in their jurisdiction.


Copyright


This article is either an original work created by 2Firsts or a reproduction from third-party sources with proper attribution. All copyrights and usage rights belong to 2Firsts or the original content provider. Unauthorized reproduction, distribution, or any other form of unauthorized use by any individual or organization is strictly prohibited. Violators will be held legally accountable.

For copyright-related inquiries, please contact: info@2firsts.com


AI Assistance Disclaimer


This article may have been enhanced using AI tools to improve translation and editorial efficiency. However, due to technical limitations, inaccuracies may occur. Readers are encouraged to refer to the cited sources for the most accurate information.

We welcome any corrections or feedback. Please contact us at: info@2firsts.com
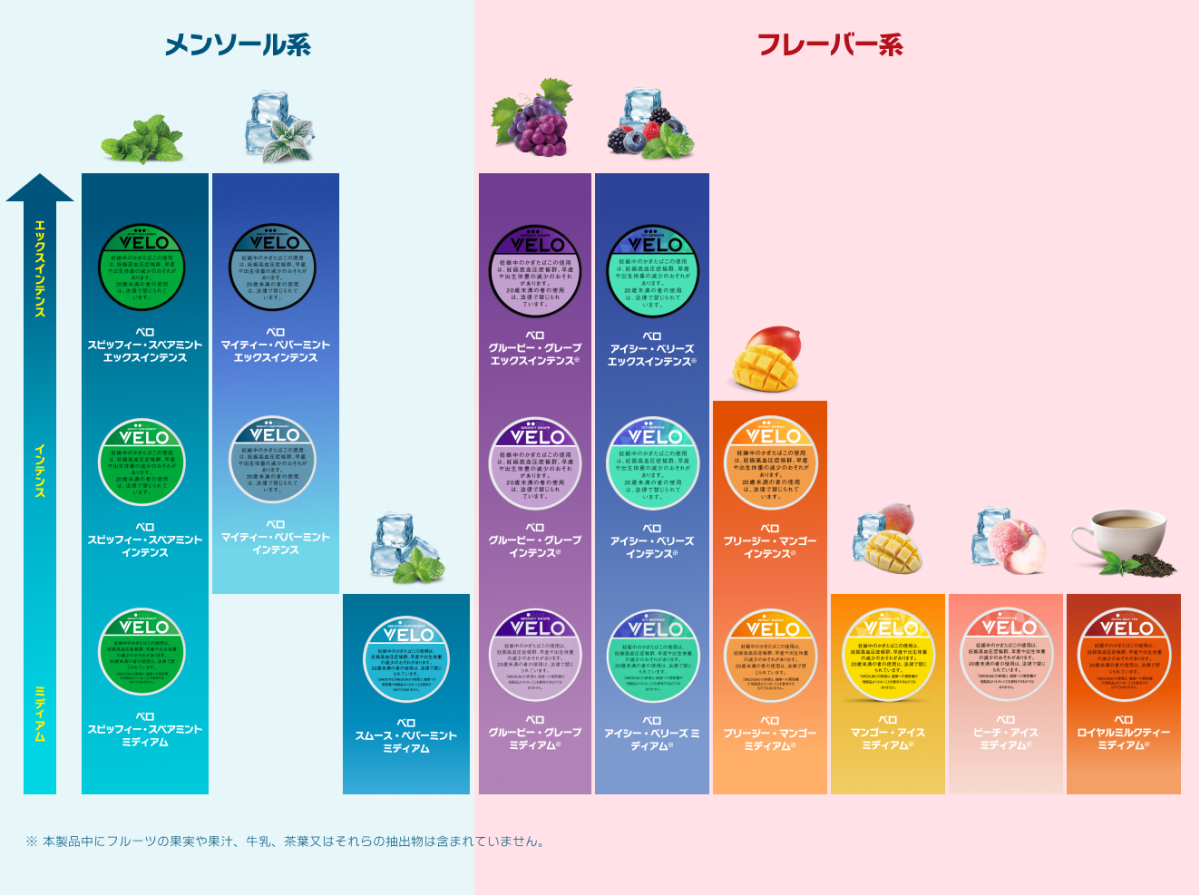
Product | BAT Revises Japan's VELO Convenience Store Lineup, Adding ¥380 Mango Pouches as Selected SKUs Exit
British American Tobacco's Japanese subsidiary, BAT Japan, launched VELO Mango Ice Medium on November 2, 2026, with distribution expanding to selected 7-Eleven, FamilyMart, NewDays and Seicomart stores from November 3. The new oral tobacco product contains 15 pouches per can and retails for ¥380, featuring a mango and cooling flavor profile at Medium intensity. At the same time, BAT Japan raised prices on multiple existing VELO products from ¥360 to ¥380 per can and withdrew selected SKUs from convenience store distribution without discontinuing them entirely. The changes affect product assortment, pricing and retail channel allocation.
product
Nov.04
Why Does JPMorgan Favor BAT Over Philip Morris Despite Forecasting Slower Growth of 3.9% Versus 6.2%?
JPMorgan resumed equity research coverage of British American Tobacco (BAT), Philip Morris International (PMI) and Imperial Brands in November 2026, assigning BAT an Overweight rating and the other two companies Neutral ratings. The bank forecasts like-for-like sales growth of 3.9% for BAT and 6.2% for PMI in 2027, but estimates the two companies will trade at approximately 11 times and 21 times 2027 earnings, respectively. JPMorgan cited BAT's improving position in US nicotine pouches and vaping products as a driver of its investment outlook. BAT reported a 220% constant-currency increase in US modern oral nicotine revenue in the first half of 2026, while PMI's ZYN US shipments returned to growth in the third quarter. Imperial expects NGPs to represent 4% to 5% of sales and has expanded its oral portfolio through acquisitions.
Capital Markets
Nov.12
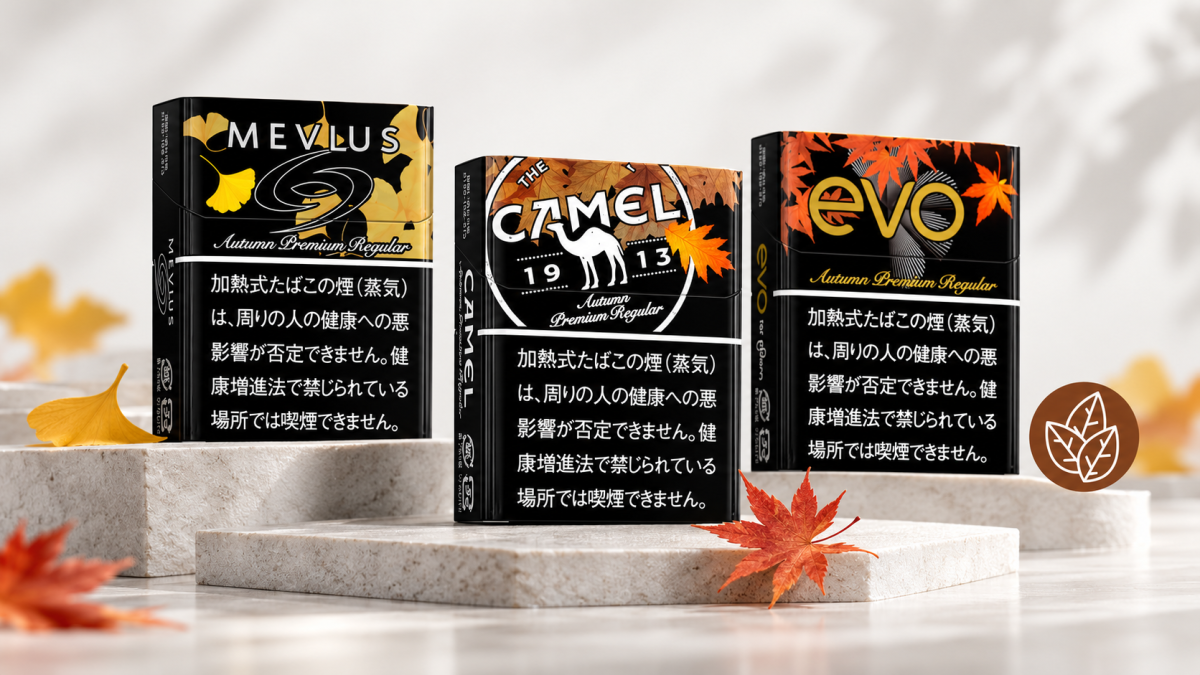
Product | JT Launches Three Autumn-Limited Ploom Tobacco Sticks in Japan Across EVO, MEVIUS and CAMEL Brands
Japan Tobacco Inc. (JT) launched three limited-edition autumn tobacco sticks for its Ploom heated tobacco devices in Japan on October 16, 2026, under the EVO, MEVIUS and CAMEL brands. All three are regular tobacco variants with seasonal packaging. Each pack contains 20 sticks, priced at ¥620, ¥590 and ¥570, respectively, including tax. The products are compatible with all Ploom devices and are sold in limited quantities exclusively through the CLUB JT online store while supplies last.
product
Oct.20
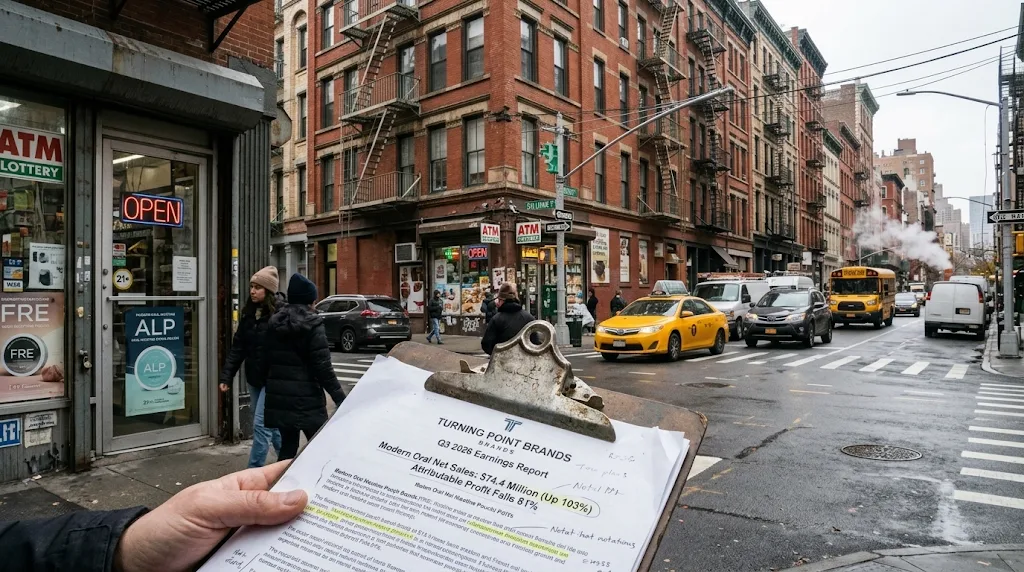
Turning Point Brands Q3 Modern Oral Net Sales Rise 103% to $74.4 Million as Attributable Profit Falls 81%
Turning Point Brands (TPB) reported third-quarter 2026 Modern Oral net sales of $74.4 million on November 9, up 102.9% year over year and representing 49.2% of consolidated net sales. Total company net sales rose 27.0% to $151.1 million, while net income attributable to TPB declined 81.4% to $3.93 million. The company is expanding the US retail presence of its FRE and ALP nicotine pouch brands and expects its Modern Oral chain-store footprint to grow by more than 70% during 2026. Selling, general and administrative expenses increased 69.1% to $75.3 million, while PMTA-related expenses reached approximately $3.15 million and manufacturing start-up costs totaled about $593,000. ALP plans to open a branded pop-up in New York City's SoHo neighborhood on November 13, alongside a marketing campaign extending into January 2027. TPB owns 50% of ALP but consolidates the venture in its financial statements.
company
Nov.11
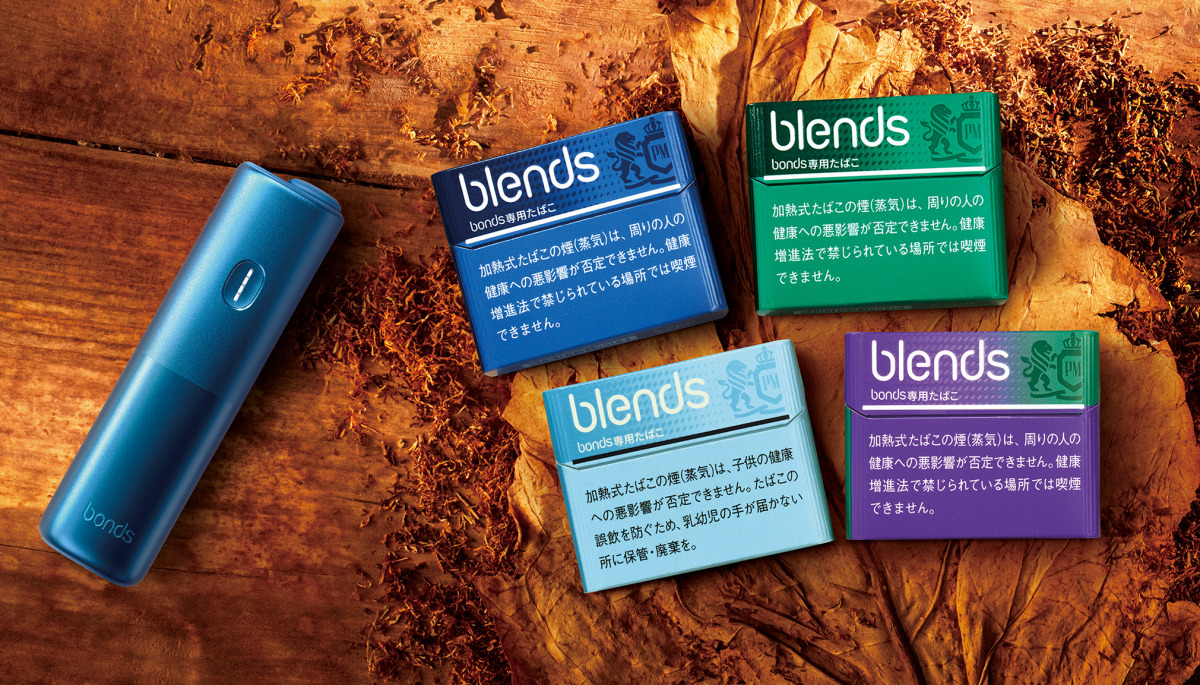
Beyond IQOS ILUMA, PMI Expands Lower-Priced BONDS Heated Tobacco Platform: Seven Markets Added in Q3, With Rollouts in Japan, Europe and North Africa
Philip Morris International (PMI) is expanding the international footprint of BONDS by IQOS, its lower-priced heated tobacco platform. The company's third-quarter 2026 SEC filing shows that BONDS devices and BLENDS tobacco sticks were available in 15 markets at the end of September, up from eight at the end of June. In November, PMI announced plans to extend sales from three to 17 Japanese prefectures and introduced BONDS in Spain and Morocco. The platform uses ROUNDHEAT external heating technology and proprietary tobacco sticks, separate from the IQOS ILUMA system. In Japan, BONDS retails for ¥2,980, approximately 25% below ILUMA i ONE, while BLENDS costs ¥570 per pack. PMI management says BONDS targets cigarette smokers who have not adopted heated tobacco. Separate sales and revenue figures remain undisclosed.
company
Nov.06
Inside Nicotine-Pouch M&A Through Imperial's Yoik Deal: Latham, KPMG, PwC, Goldman Sachs and Morgan Stanley Form the Adviser Lineup
Imperial Brands' acquisition of Swedish Helwit owner Yoik Group AB has highlighted the professional-services firms supporting cross-border oral nicotine M&A. Latham & Watkins and KPMG advised Imperial, while PwC and TM & Partners advised Yoik. KPMG also appeared on Imperial's acquisition of Black Buffalo earlier in 2026, while PwC played an extensive role in KT&G's acquisition of Swedish nicotine-pouch company Another Snus Factory. Imperial's public disclosures put the global modern oral nicotine delivery market at approximately £8.8 billion in retail sales and 23.5 billion pouches in 2024
Sep.20