Review: Evolution of Cigarette Consumption Tax Policy in China (Pt.2)

Aug.16.2024
 Review: Evolution of Cigarette Consumption Tax Policy in China (Pt.2)
China adjusts tobacco consumption tax in 2009 and 2015 to ease economic pressure, focusing on production and wholesale.

Special announcement:

"2FIRSTS" has been authorized for reprint by the source media (WeChat public account "huoxingliaoran").

The entire article represents the perspective and stance of huoxingliaoran.


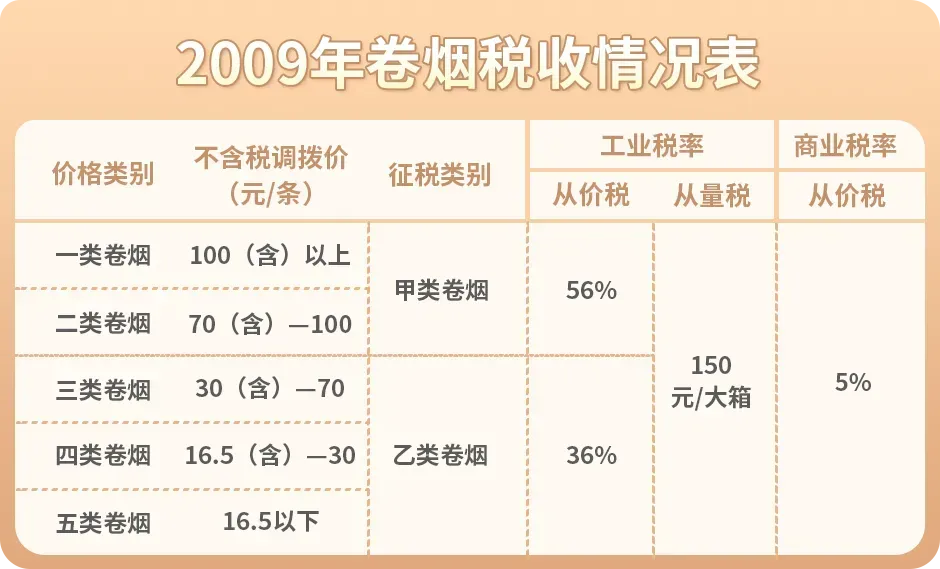
Adjustment of cigarette consumption tax in 2009


The main content includes two aspects: first, adjusting the collection process from the production stage to the production and wholesale stages. An additional ad valorem tax of 5% will be levied in the wholesale stage. Second, adjusting the tax rates in the production stage. For Class A cigarettes with a retail price of 70 yuan or above (including 70 yuan), the tax rate will be adjusted to 56%; for Class B cigarettes with a retail price below 70 yuan, the tax rate will be adjusted to 36%. This adjustment is part of the country's macroeconomic control measures to address the severe economic situation caused by the 2008 financial crisis and alleviate the pressure on national fiscal revenue. Following the principle of "price, tax, and revenue" linkage, it rationalizes cigarette pricing relationships and creates a fair competitive market environment. The tax increase this time is mainly absorbed within the industry and has not had a significant impact on cigarette sales.
 

 Review: Evolution of Cigarette Consumption Tax Policy in China (Pt.2)
Image source: huoxingliaoran


In 2015, the fifth adjustment of cigarette consumption tax was implemented.


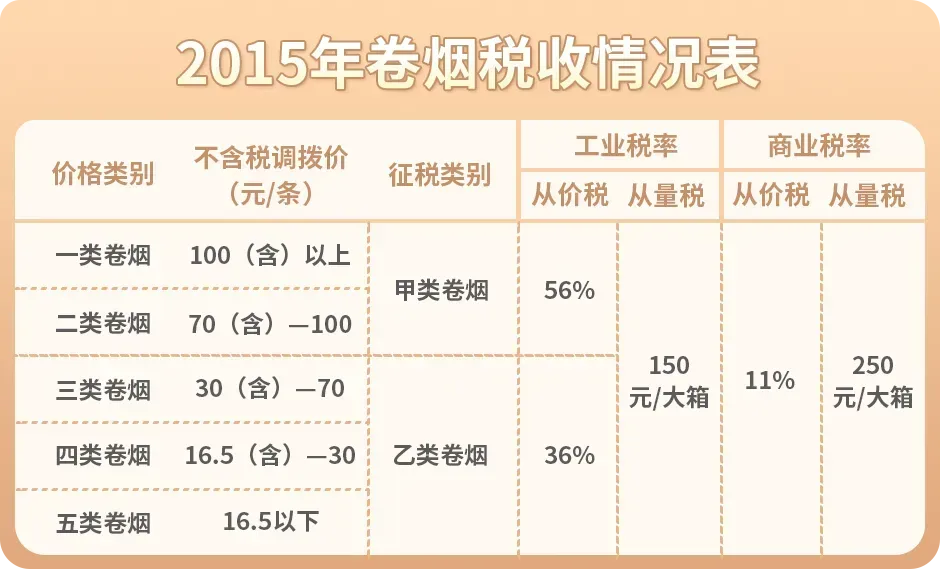
The tax adjustment policy that took effect on May 10, 2015, increases the ad valorem tax rate on Class A and B cigarettes in the wholesale sector from 5% to 11%, and imposes an additional specific tax of 0.005 yuan per cigarette (250 yuan per carton) at the wholesale level. The final tax adjustment plan for cigarettes determined by the State Administration includes a uniform 6% increase in wholesale prices for all cigarettes, while simultaneously raising the recommended retail price according to a principle that the retail gross margin should not be less than 10%. After the tax adjustment, the ad valorem tax rate in the wholesale sector for cigarettes increases by 6 percentage points, in addition to the new specific tax and urban construction tax, education surcharge, etc., resulting in an increase of RMB 80 billion in central government revenue from tobacco taxes annually on top of natural growth.
 

 Review: Evolution of Cigarette Consumption Tax Policy in China (Pt.2)
Image source: huoxingliaoran


In 2015, the increase in cigarette consumption tax was achieved through raising prices, unlike in 2009 when the industry absorbed the increase internally. By raising prices, the adjusted taxes were passed on to consumers, which had a positive impact on tobacco control. Additionally, a volume-based tax was imposed on commercial wholesalers, increasing their tax contribution significantly and boosting their financial contribution to the government. As a result, the impact of this tax adjustment on tobacco was greater than previous instances.
 

 Review: Evolution of Cigarette Consumption Tax Policy in China (Pt.2)
Image source: huoxingliaoran


Characteristics of the adjustments to cigarette consumption tax in our country


Analyzing the situation of successive tobacco tax increases in our country, several characteristics are evident:


Time intervals: There is a gap of 3-8 years between the implementation of policies in 1994, 1998, 2001, 2009, and 2015. Policies are typically implemented in May of the respective year.


Presenting the ongoing process of continuous reform and improvement in tax types, tax rates, and collection procedures.


In 1994 and 1998, reforms were made to cigarette taxes and rates. In 2001 and 2009, adjustments were mainly made to tax rates and collection processes, all of which were absorbed by the industry. In 2015, tax adjustments were made in conjunction with price adjustments, marking the first time that taxes were passed on to consumers through price increases.


Presenting the process of expanding the tax collection process from industrial to commercial sectors. Not only are taxes levied based on quantity and value in the industrial sector, but they are also levied based on quantity and value in the commercial sector.


Conclusion


The tax adjustments in 2009 and 2015 marked the maturity and deepening of China's tobacco taxation policy. Through the implementation of these policies, we have not only witnessed changes in the market, but also gained a clearer insight into possible future policy directions. The ongoing transformation of the industry is also worth our attention and contemplation.

We welcome news tips, article submissions, interview requests, or comments on this piece.

Please contact us at info@2firsts.com, or reach out to Alan Zhao, CEO of 2Firsts, on LinkedIn


Notice

1.  This article is intended solely for professional research purposes related to industry, technology, and policy. Any references to brands or products are made purely for objective description and do not constitute any form of endorsement, recommendation, or promotion by 2Firsts.

2.  The use of nicotine-containing products — including, but not limited to, cigarettes, e-cigarettes, nicotine pouchand heated tobacco products — carries significant health risks. Users are responsible for complying with all applicable laws and regulations in their respective jurisdictions.

3.  This article is not intended to serve as the basis for any investment decisions or financial advice. 2Firsts assumes no direct or indirect liability for any inaccuracies or errors in the content.

4.  Access to this article is strictly prohibited for individuals below the legal age in their jurisdiction.


Copyright


This article is either an original work created by 2Firsts or a reproduction from third-party sources with proper attribution. All copyrights and usage rights belong to 2Firsts or the original content provider. Unauthorized reproduction, distribution, or any other form of unauthorized use by any individual or organization is strictly prohibited. Violators will be held legally accountable.

For copyright-related inquiries, please contact: info@2firsts.com


AI Assistance Disclaimer


This article may have been enhanced using AI tools to improve translation and editorial efficiency. However, due to technical limitations, inaccuracies may occur. Readers are encouraged to refer to the cited sources for the most accurate information.

We welcome any corrections or feedback. Please contact us at: info@2firsts.com
South Korea Extends Vape Rules to Unmanned Stores After Bringing Synthetic Nicotine Under Tobacco Law
South Korea's Ministry of Gender Equality and Family said on September 14 that it plans to designate unmanned e-cigarette stores as businesses where minors are prohibited from entering or working. Operators would be required to verify customers' ages and display notices restricting access by minors. The proposal is open for public comment through October 6. The move follows an April expansion of South Korea's statutory tobacco definition that brought products made with natural or synthetic nicotine under the Tobacco Business Act. Nicotine-free liquids and products using nicotine analogues such as 6-methylnicotine, however, remain an emerging regulatory issue.
Sep.21
US ITC Judge Finds Glas Infringed Two JUUL Vape Patents, Recommends Restrictions on Related Imports——Glas Received FDA Marketing Authorization for Four Vape Pods in May 2026; Proposed Restrictions Remain Under Commission Review
A U.S. International Trade Commission (USITC) administrative law judge issued an initial determination on October 20, 2026, finding that certain Glas vaping devices, cartridges and components infringed 12 claims across two patents asserted by JUUL, constituting a violation of Section 337 of the Tariff Act of 1930. The judge recommended a limited exclusion order and a cease and desist order against the Glas respondents. Five months earlier, the FDA authorized four Glas e-cigarette pods, including mango, blueberry and two menthol variants. The patent investigation concerns device and cartridge structures and is separate from FDA premarket review. The proposed import restrictions have not become final, and their product-level scope remains unresolved.
company
Nov.05
Altria Showcases Ploom, Marlboro Heated Tobacco Sticks and Non-Nicotine Energy Products at NACS Show 2026
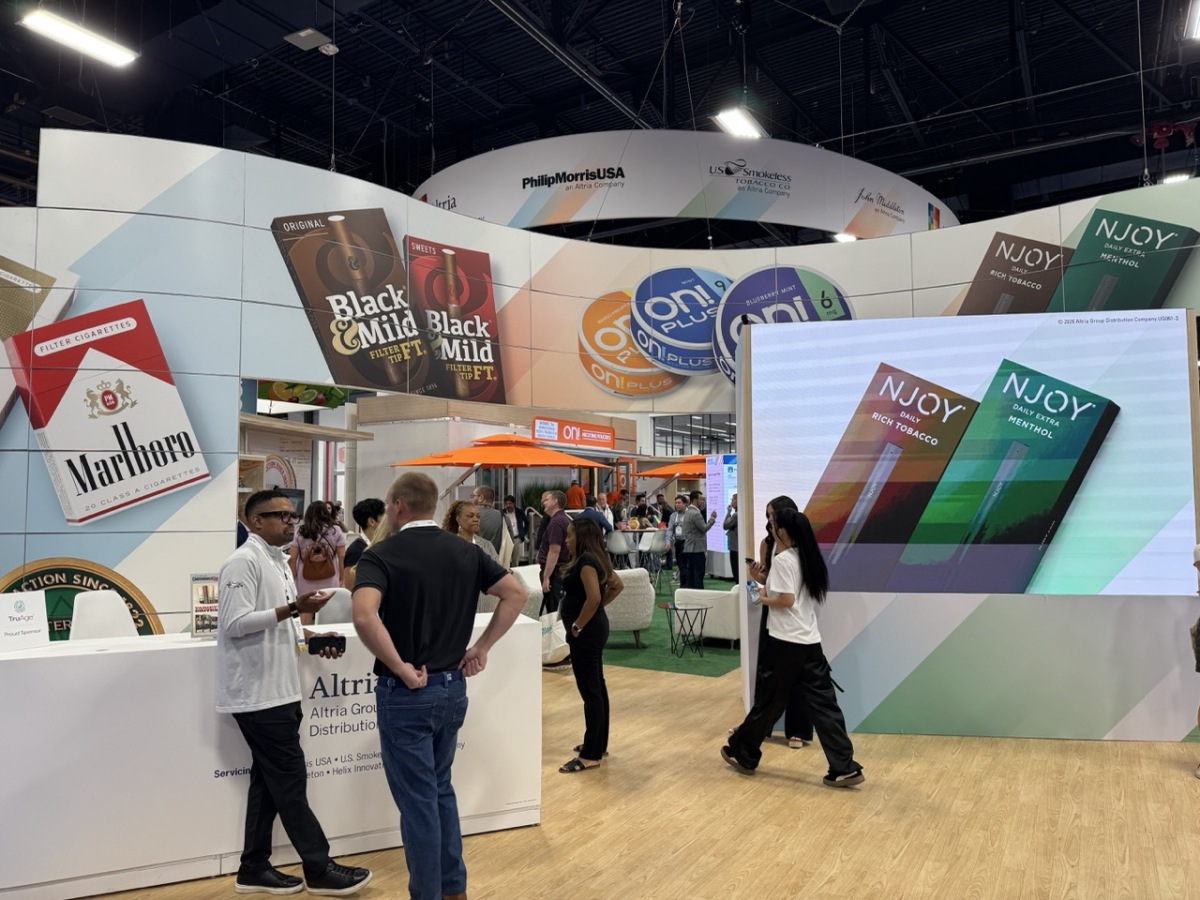
At the 2026 NACS Show, Altria displayed Ploom devices alongside imagery of Marlboro-branded heated tobacco sticks, while also featuring RIOT Energy and Proper Wild non-nicotine products. The booth showcased on! PLUS nicotine pouches, including 12 mg variants not listed among FDA-authorized products as of October 9, and NJOY e-cigarettes. Altria also presented convenience-store traffic figures highlighting its retail presence. 2Firsts examines the company's expanded product portfolio, non-nicotine business activities and the regulatory status of products displayed at the show.
EXPO
Oct.10
FRE and ALP Push Modern Oral to 48% of Q2 Sales as Turning Point Brands Changes CEO and Lowers Profit-Guidance Ceiling
Turning Point Brands said Executive Chairman David E. Glazek will become CEO on October 1, replacing Graham Purdy, who is stepping down for personal reasons. The company narrowed its 2026 adjusted EBITDA outlook to $70 million-$80 million from $70 million-$90 million while maintaining Modern Oral gross sales guidance of $330 million-$350 million and net sales guidance of $260 million-$270 million. In the second quarter, Modern Oral net sales rose 128% to $68.4 million and accounted for 48% of company-wide net sales. Adjusted EBITDA fell 50% year over year. TPB shares closed about 10% lower on September 21.
Market
Sep.22 by 2Firsts Perspectives
On-Site Report | After FDA Announces Review of PMTA Framework, CTP Director Details Reform Priorities
FDA CTP Director Bret Koplow used his FDLI keynote in Washington to outline how the agency is rethinking the PMTA framework. He discussed category-specific review, nicotine pouch and sPMTA pilots, AI-assisted review, a 70% reduction in pending applications, and a major staffing constraint: CTP currently has only nine scientific review teams. He also reaffirmed tobacco harm reduction while stressing youth protection, flavored products, risk communication, and the challenge of unauthorized e-cigarettes.
Regulations
Oct.06
2Firsts First Look|China to End VAT Export Rebates on Vape Devices and Nicotine in April 2027, Following Earlier Removal for HTP Devices and Nicotine Vapes
China's Ministry of Finance and State Taxation Administration announced on October 12, 2026, that value-added tax (VAT) export rebates for vape devices, nicotine and its salts, and certain non-combustible inhalation products will be eliminated from April 1, 2027. The measure adds four tobacco- and nicotine-related customs codes, including 8543400010, which covers vape devices and qualifying empty pods. China previously eliminated rebates for nicotine-containing vaping products and devices under code 8543400090 in April 2026. According to industry classification information held by 2Firsts, the latter currently corresponds to heated tobacco devices. Export excise tax refund and exemption arrangements will remain unchanged.
Special Report
Oct.12