Review: Evolution of Cigarette Consumption Tax Policy in China (Pt.1)

Industry Insight by Huoxing Liaoran, translated by 2FIRSTS Reese & edited by Sophia
Aug.09.2024
Review: Evolution of Cigarette Consumption Tax Policy in China (Pt.1)
Since the "System of Tax Disbribution" reform in 1994, China's cigarette consumption tax policy has undergone several significant adjustments. These changes not only reflect the evolution of the economic situation but also reveal the profound impact of policy makers on the structure of the tobacco industry. Let's review how these policies, from the initial uniform tax rate to the complex graded tax system, have shaped today's cigarette market.

Special announcement:

2FIRSTS have been authorized by Source Media (WeChat Public Account "Huoxing Liaoran") to republish;

The entire text represents the views and stance of Huoxing Liaoran.


The third plenary session of the 20th Central Committee of the Communist Party of China was held in Beijing from July 15th to 18th, 2024. At the session, the Central Committee heard and discussed a report on the work of the Political Bureau, emphasized on further comprehensive and deepening reforms, advancing issues related to China's modernization, and considered and adopted the Resolution of the Central Committee of the Communist Party of China on Further Deepening Reform Comprehensively to Advance Chinese Modernization.
 

Review: Evolution of Cigarette Consumption Tax Policy in China (Pt.1)


Speculation in the public suggests that the country is soon to introduce a trillion-level consumption tax reform. China's consumption tax is a central tax, all of which is directly handed over to the state. According to data from the Ministry of Finance, in 2023, the national consumption tax revenue was 1.61 trillion yuan, accounting for 8.9% of the overall tax revenue. The consumption tax reform means that when local governments no longer have income from selling land, the nation will allocate some of the consumption tax revenue to them.


Cigarette consumption tax is the main part of the consumption tax. Now let's take a look at the changes in cigarette consumption tax policy together.


China's Adjustments to Cigarette Consumption Tax


The tobacco consumption tax in our country has been adjusted five times in 1994, 1998, 2001, 2009, and 2015.


1.Before 1994, tobacco was subject to the same 60% product tax as other industries.


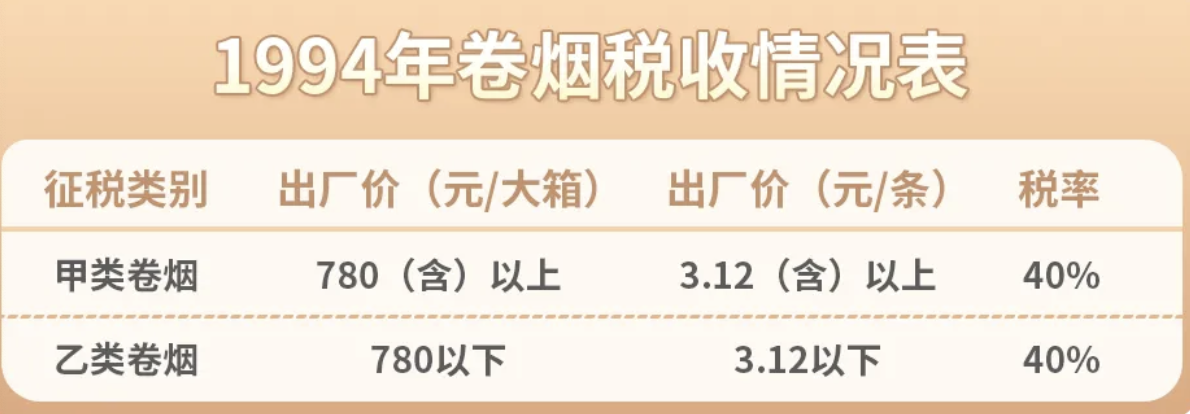
After the implementation of the "System of Tax Disbribution" in 1994, the product tax was changed to Value Added Tax, and a new cigarette consumption tax was added. All types of cigarettes were taxed at a uniform rate of 40% based on the factory price. Through the implementation of this policy, tobacco production enterprises were encouraged to produce more high-end cigarettes with higher profits, shifting the product structure from low-end to high-end. Brands such as "Furong Wang" (1994), "Huanghelou" (1995), "Jiaozhi" (1995), and "Liqun" (1995) were born or revamped during this period.
 

Review: Evolution of Cigarette Consumption Tax Policy in China (Pt.1)
Image Source | Huoxing Liaoran


2. In 1998, the cigarette consumption tax system was reformed once again.


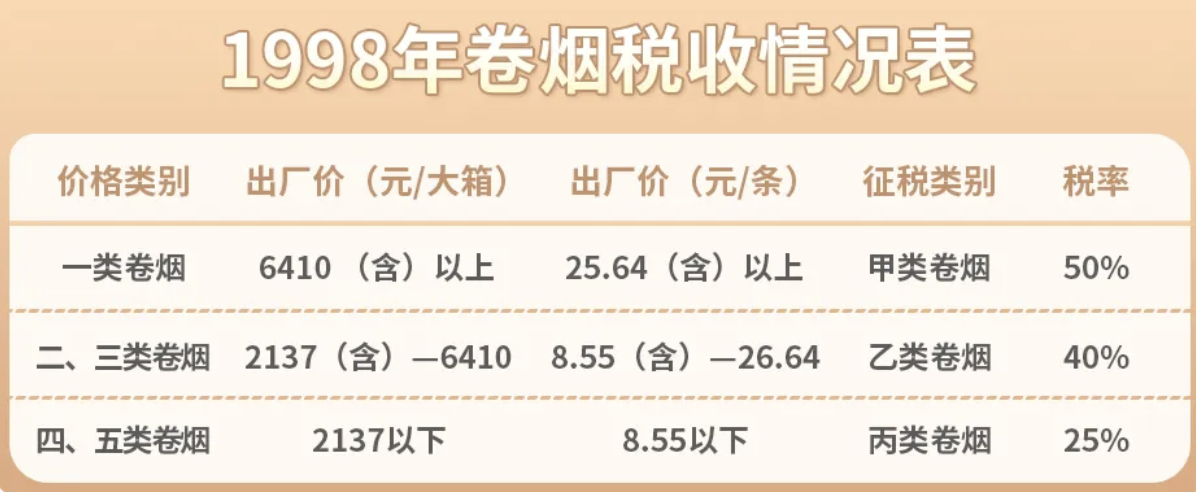
The tax system had changed from a single tax rate to a tiered tax rate, with three tiers: 50% for Category 1 tobacco, and 40% for Category 2 and 3, and 25% for Category 4 and 5. Following the implementation of this policy, sales of low-grade cigarettes had significantly increased, and some small and medium-sized tobacco factories had experienced a revival due to the tax reduction. During this period, tobacco consumption tax had been levied based on the ex-factory price, and was only collected at the production stage.
 

Review: Evolution of Cigarette Consumption Tax Policy in China (Pt.1)
Image Source | Huoxing Liaoran


3. In 2001, the adjustment of cigarette consumption tax was implemented using a composite taxation method that combined both volume-based and value-based taxes.


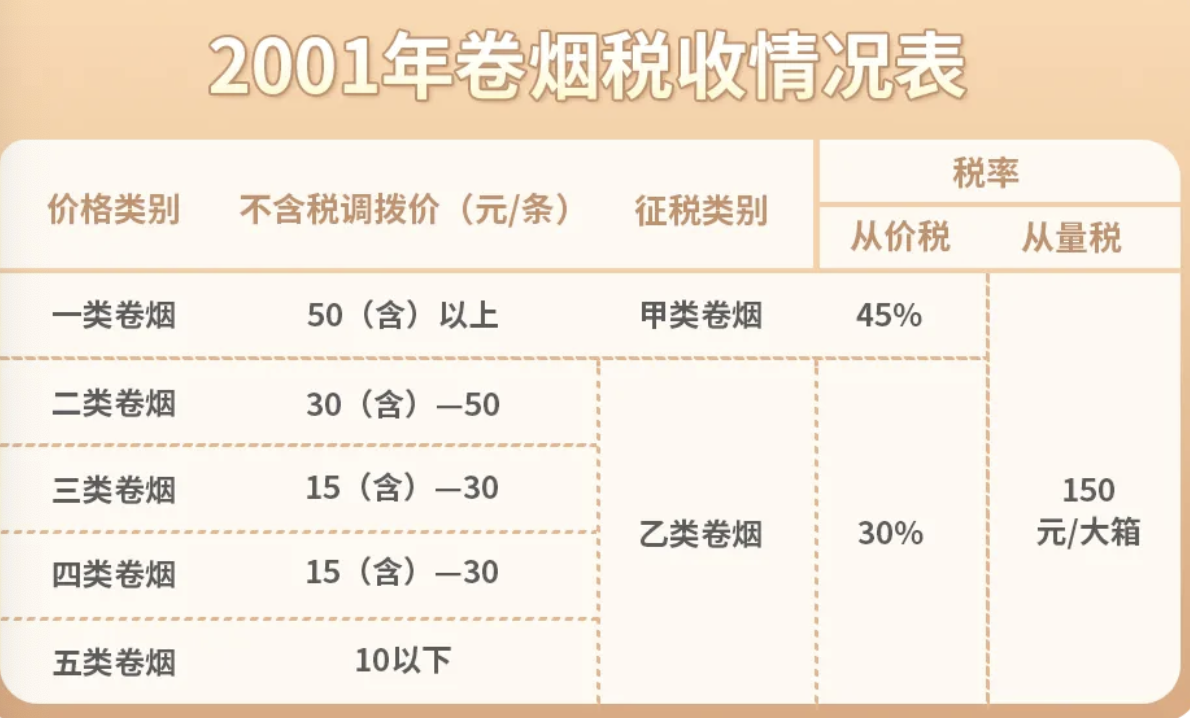
A fixed tax of 150 yuan was levied on every 50,000 cigarettes, while an ad-valorem tax was adjusted to two tiers: 45% for cigarettes with an allocation price of 50 yuan or more, and 30% for cigarettes with an allocation price below 50 yuan. Following the tax reform, the tax rate for low-end cigarettes had been increased from 25% to 30%, along with an additional fixed tax of 150 yuan per box, significantly increasing the tax burden on low-end cigarettes and reflecting a policy focused on supporting larger enterprises. Small and medium-sized enterprises producing less than 100,000 boxes of low-end cigarettes annually were experiencing severe losses, leading to closures and conversions, allowing for smoother restructuring of the cigarette industry.
 

Review: Evolution of Cigarette Consumption Tax Policy in China (Pt.1)
Image Source | Huoxing Liaoran


Conclusion


Looking back at the tax reforms from 1994 to 2001, we can see how policies have aimed to strike a balance between market demand and economic conditions. These adjustments not only altered the market landscape of the tobacco industry, but also laid the foundation for future policy making. In the next edition, I will delve into the adjustments made in 2009 and 2015 and their far-reaching impacts on the industry, so stay tuned.


We welcome news tips, article submissions, interview requests, or comments on this piece.

Please contact us at info@2firsts.com, or reach out to Alan Zhao, CEO of 2Firsts, on LinkedIn


Notice

1.  This article is intended solely for professional research purposes related to industry, technology, and policy. Any references to brands or products are made purely for objective description and do not constitute any form of endorsement, recommendation, or promotion by 2Firsts.

2.  The use of nicotine-containing products — including, but not limited to, cigarettes, e-cigarettes, nicotine pouchand heated tobacco products — carries significant health risks. Users are responsible for complying with all applicable laws and regulations in their respective jurisdictions.

3.  This article is not intended to serve as the basis for any investment decisions or financial advice. 2Firsts assumes no direct or indirect liability for any inaccuracies or errors in the content.

4.  Access to this article is strictly prohibited for individuals below the legal age in their jurisdiction.


Copyright


This article is either an original work created by 2Firsts or a reproduction from third-party sources with proper attribution. All copyrights and usage rights belong to 2Firsts or the original content provider. Unauthorized reproduction, distribution, or any other form of unauthorized use by any individual or organization is strictly prohibited. Violators will be held legally accountable.

For copyright-related inquiries, please contact: info@2firsts.com


AI Assistance Disclaimer


This article may have been enhanced using AI tools to improve translation and editorial efficiency. However, due to technical limitations, inaccuracies may occur. Readers are encouraged to refer to the cited sources for the most accurate information.

We welcome any corrections or feedback. Please contact us at: info@2firsts.com
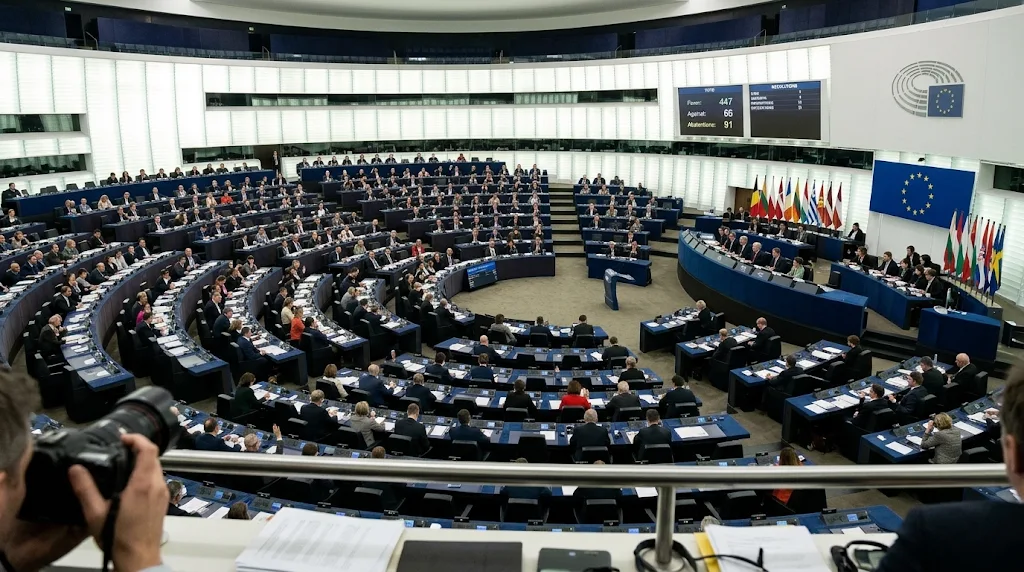
EU TPD Revision May Slip to 2027: Parliament Backs Wider Nicotine Rules by 447 Votes as Commission Impact Assessment Reportedly Receives Negative Opinion
On Nov 12, 2026, the European Parliament adopted a resolution on implementing Europe’s Beating Cancer Plan by 447 votes to 66, with 91 abstentions, urging the European Commission to speed up revisions to the Tobacco Products Directive (TPD) and Tobacco Advertising Directive (TAD). Parliament called for broader regulation of e-cigarettes, heated tobacco, nicotine pouches and other emerging nicotine products, proposing measures on packaging, health warnings, flavors, ingredient reporting, online age verification, digital marketing and premarket health impact assessments. EUNews and others reported that the Commission’s Regulatory Scrutiny Board (RSB) issued a negative opinion on the revisions’ impact assessment on Nov 9. The Commission had scheduled the initiative for December 2026, but the reported setback could push the legislative proposal into 2027. No revised official timetable has been announced, and Parliament’s resolution does not amend existing EU law.
Regulations
Nov.19
UK Vape Duty Starts in October as Hayati, DOJO and Others Launch Lower-Capacity Products With Lower Per-Unit Tax
The UK's Vaping Products Duty will take effect on October 1, 2026, at a flat rate of £2.20 per 10ml of vaping liquid. Ahead of implementation, DOJO, PIXL and Hayati have introduced or been reported to be adding lower-capacity tiers alongside larger products. DOJO has added a 6ml BLAST7K Fresh below its 10ml BLAST10K Fresh, PIXL offers both a 12ml 8000 and a 6ml 5K, while retailer Ninja Vapes says Hayati is preparing a 7ml 4K alongside its existing 12ml 6K. The pattern points to a growing lower-capacity tier in the UK market, although the brands have not all explicitly linked the changes to the new duty.
Sep.23
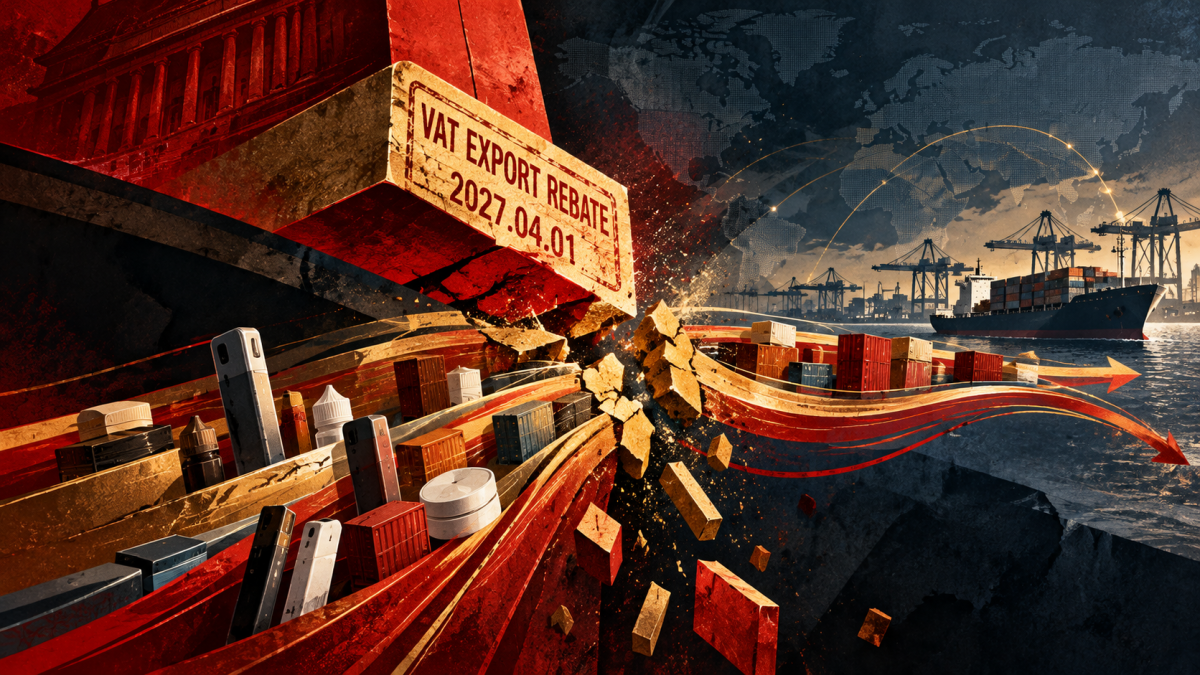
2Firsts First Look|China to End VAT Export Rebates on Vape Devices and Nicotine in April 2027, Following Earlier Removal for HTP Devices and Nicotine Vapes
China's Ministry of Finance and State Taxation Administration announced on October 12, 2026, that value-added tax (VAT) export rebates for vape devices, nicotine and its salts, and certain non-combustible inhalation products will be eliminated from April 1, 2027. The measure adds four tobacco- and nicotine-related customs codes, including 8543400010, which covers vape devices and qualifying empty pods. China previously eliminated rebates for nicotine-containing vaping products and devices under code 8543400090 in April 2026. According to industry classification information held by 2Firsts, the latter currently corresponds to heated tobacco devices. Export excise tax refund and exemption arrangements will remain unchanged.
Special Report
Oct.12
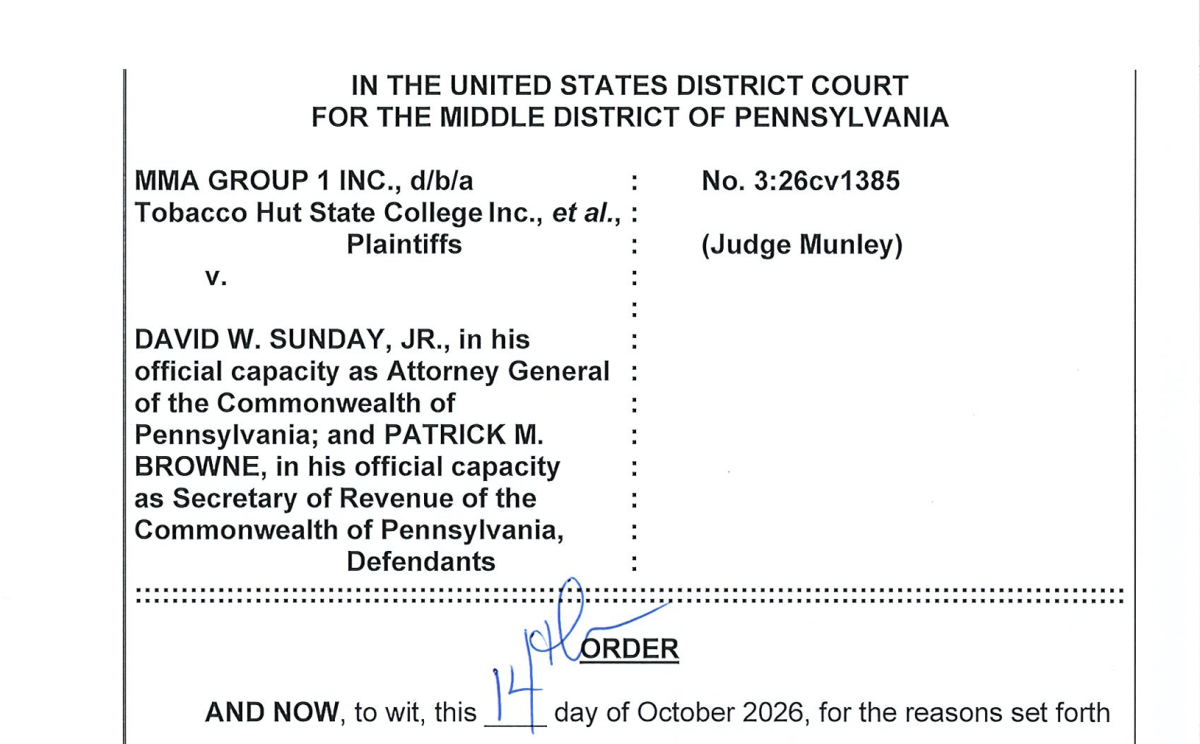
Pennsylvania Vape Directory Law Survives Court Challenge From Nova Distro and Others Amid Similar Rulings Across States
A U.S. federal court upheld Pennsylvania's vape directory law on October 14, rejecting a challenge brought by Nova Distro, 101 Distributors and companies operating Tobacco Hut retail stores. Court records show that vaping accounts for about 60% of Tobacco Hut's profits and that the chain held approximately $2 million in inventory potentially subject to seizure under the law as of June 2. Pennsylvania began enforcement on October 19. The ruling follows similar appellate decisions in other states, even as new research shows that unlisted vaping products continue to account for substantial sales in states with established directories.
Regulations
Oct.22
Texas Extends Tobacco Tax Interpretation to a 6-Methylnicotine Product, Citing VELO Ruling
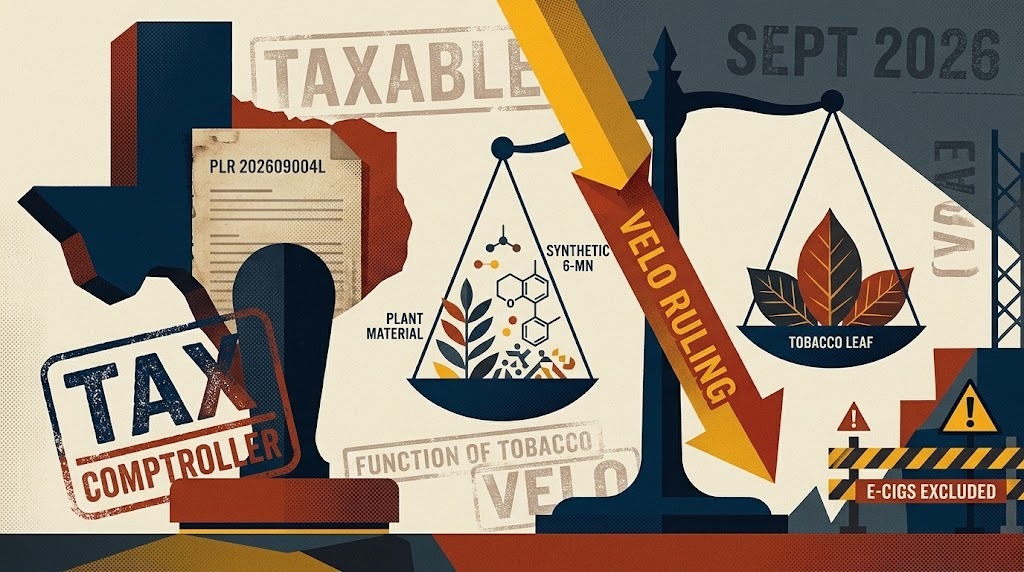
The Texas Comptroller of Public Accounts ruled in September 2026 that a combustible product made with non-tobacco plant material and 6-methylnicotine (6-MN), a synthetic nicotine analog, qualifies as a taxable tobacco product. The applicant said the product contained neither tobacco leaf nor measurable conventional nicotine. The determination applies reasoning from a May Texas Supreme Court decision involving VELO nicotine pouches, finding that the plant material and 6-MN together perform the functions of tobacco in a conventional smoking product. The ruling carries applicable tax, licensing and reporting obligations but is limited to the facts submitted by the taxpayer. It does not establish a blanket tax classification for all 6-MN products or extend the same conclusion to e-cigarettes.
Regulations
Nov.06
Product | Philip Morris Launches TEREA Bold Red and Bold Black in Germany With Level-10 Tobacco Intensity at €8 per Pack
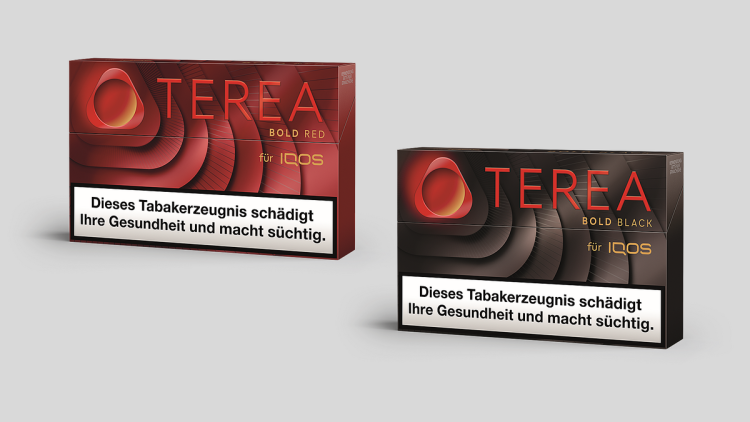
Philip Morris International (PMI) introduced TEREA Bold Red and Bold Black heated tobacco sticks in Germany in October 2026, both carrying a brand-rated tobacco-flavor intensity of 10, the highest level in the country's TEREA portfolio. Bold Red features leather and warm woody notes, while Bold Black combines woody and subtle floral notes. Both are sold in 20-stick packs at €8, approximately 2.6% above standard TEREA products. Germany's TEREA range now includes 11 flavor variants, alongside a separate 26-stick XL format priced at €10. IQOS Germany announced the new products on October 12, followed by a phased retail rollout from late October and an IQOS Club campaign running through December.
product
Nov.02