Babylon Vardex Group sues over illegal tax on ENDS.

Sep.22.2022
Babylon Vardex Group sues over illegal tax on ENDS.
Babylon Vardex Group sues Moscow court over central excise tax on liquid in electronic nicotine delivery systems.

The main distributor of Electronic Nicotine Delivery Systems (ENDS), Babylon Vardex Group, has filed a lawsuit with the Moscow Arbitration Court, declaring the behavior of the Central Excise Tax (CAT) as illegal. The latter demands payment of consumption tax for the liquid contained in the ENDS.


Artem Shevelin, the chief lawyer of Babilon LLC, has explained that in addition to paying consumption taxes on equipment, customs authorities are also requiring liquid consumption taxes to be paid on immersed evaporators. The size of these requirements, which relate to goods imported between 2020 and 2022, has not been disclosed. A preliminary hearing for the claim will take place between September and October.


CAT stated that all activities involving ENDS are legal. The Ministry of Finance also pointed out that a consumption tax must be paid on the liquid used for ENDS. It does not matter whether it is sold separately or as part of a package.


Market experts add that pressure on market participants will only push them into a gray area, rendering legal businesses unprofitable for suppliers and sellers alike. However, the current situation calls for a cross-departmental meeting to discuss ways to avoid potential double taxation issues.


On August 9th, the Russian Ministry of Industry and Trade proposed to advance the label test on nicotine liquids and electronic nicotine delivery systems, and to enforce mandatory labels for these products starting from November 1st, 2022.


Statement:


This article is compiled based on third-party information and is intended solely for industry communication and learning.


This article does not represent the views of 2FIRSTS, and 2FIRSTS cannot confirm the authenticity or accuracy of the article's content. The article's translation is solely intended for industry-specific communication and research.


Due to the limitations of our translation abilities, the translated article may not accurately reflect the original text. Therefore, readers are advised to rely on the original text for accuracy.


2FIRSTS is in full alignment with the Chinese government's positions and statements on any domestic, Hong Kong and Taiwan-related, and foreign issues.


5. The copyright of the compiled information belongs to the original media and authors. If there is infringement, please contact us for removal.


Disclaimer

This article is provided solely for professional research, industry discussion, and informational purposes. Any references to brands, companies, products, technologies, or policies are made for factual reporting and analytical purposes only, and do not constitute endorsement, recommendation, promotion, or advertising by 2Firsts.

Nicotine-containing products, including but not limited to cigarettes, e-cigarettes, heated tobacco products, and nicotine pouches, carry significant health risks. Readers are responsible for complying with all applicable laws and regulations in their respective jurisdictions, including age restrictions and access limitations.

The information contained in this article should not be regarded as investment, legal, medical, regulatory, or commercial advice. While 2Firsts strives to ensure the accuracy and reliability of its content, it does not assume liability for any direct or indirect loss arising from errors, omissions, inaccuracies, or reliance on the information contained herein.

This article is not intended for individuals below the legal age for accessing tobacco or nicotine-related information in their jurisdiction.


Copyright Notice

This article is either original content produced by 2Firsts or content reproduced, translated, summarized, or adapted from third-party sources with attribution where applicable. The intellectual property rights of the original content remain with 2Firsts or the respective original rights holders.

No individual or organization may copy, reproduce, distribute, republish, modify, translate, or otherwise use this content without prior authorization. Any unauthorized use may result in legal action.

For copyright-related inquiries, corrections, or removal requests, please contact: info@2firsts.com.


AI-Assisted Translation and Editing Notice

Portions of this article may have been translated, edited, or reviewed with the assistance of artificial intelligence tools to improve efficiency and readability. Due to the limitations of AI-assisted translation and editing, discrepancies, omissions, or inaccuracies may exist when compared with the original source.

Where applicable, readers are advised to refer to the original source for the most complete and accurate information. If you identify any errors or believe that any content infringes upon your rights, please contact us at info@2firsts.com, and we will review and address the matter promptly.
South Korea Constitutional Court Upholds Volume-Based E-Liquid Tax, With Challenged Rates at KRW 370 and KRW 628 per Milliliter
South Korea's Constitutional Court has upheld fixed taxes on nicotine-containing e-cigarette liquids based on solution volume, ruling that challenged provisions imposing KRW 370 per milliliter in individual consumption tax and KRW 628 per milliliter in tobacco consumption tax do not violate the Constitution. The cases stemmed from historical disputes involving importers that reported nicotine as being extracted from tobacco stems rather than leaves. South Korea has since broadened its tobacco definition to include synthetic nicotine, while current tax laws provide reduced rates for certain products not derived from tobacco.
Sep.18
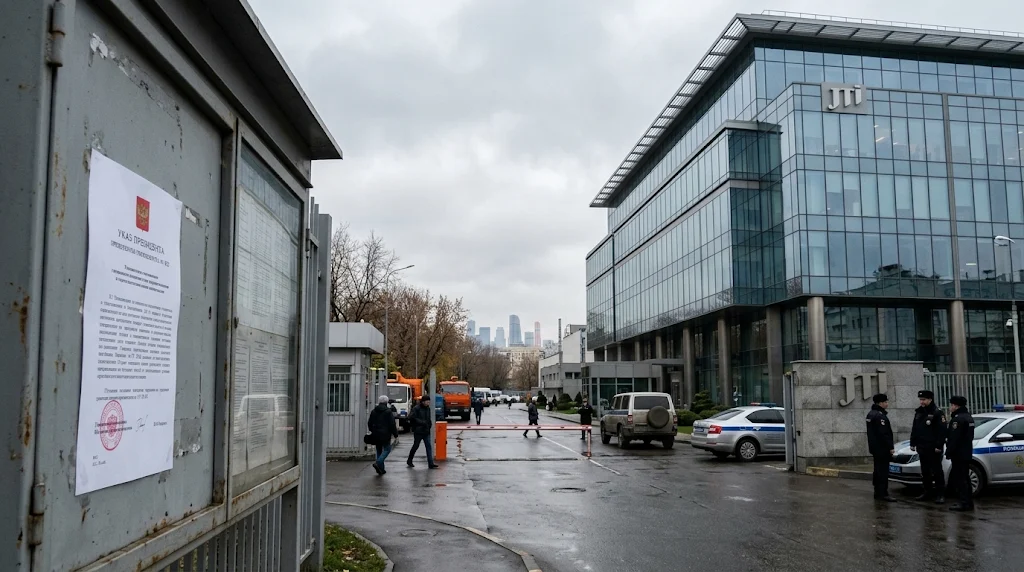
Russia Expands Temporary Administration of JTI Assets in Second Round: From Four to All Seven Russian Entities, With Approximately $9.5 Billion in Related Assets
Japan Tobacco Inc. (JT) confirmed on November 9, 2026, that all seven of its Russian entities had been placed under temporary administration after a second presidential decree added three companies to the four designated a day earlier. The additional entities are associated with importing, management, holdings and the former supply of Ploom heated-tobacco devices. JT disclosed approximately ¥1.5 trillion in Russian business-related assets as of September 30, including ¥360 billion in cash and deposits, and approximately ¥200 billion in liabilities. Under its revised FY2026 forecast, Russia accounts for about 25% of adjusted operating profit. JT said operations in Russia were continuing, while the financial impact remained under assessment.
company
Nov.09
JTI Proposes 25-Cent Irish Cigarette Tax Increase, Says It Could Raise €45 Million
Japan Tobacco International's Irish business has proposed a €0.25 tax increase on a pack of 20 cigarettes in its pre-Budget 2027 submission, below the €0.50-or-more increases typically imposed in recent Irish budgets. JTI says the proposal could generate around €45 million in additional Exchequer revenue while limiting further movement toward illicit and non-Irish-tax-paid tobacco. Revenue's existing estimate for a comparable €0.25 increase, including pro-rata rises on other tobacco products, is about €18 million for a full year.
JTI
Sep.18 by 2Firsts Perspectives
Product | BAT Revises Japan's VELO Convenience Store Lineup, Adding ¥380 Mango Pouches as Selected SKUs Exit
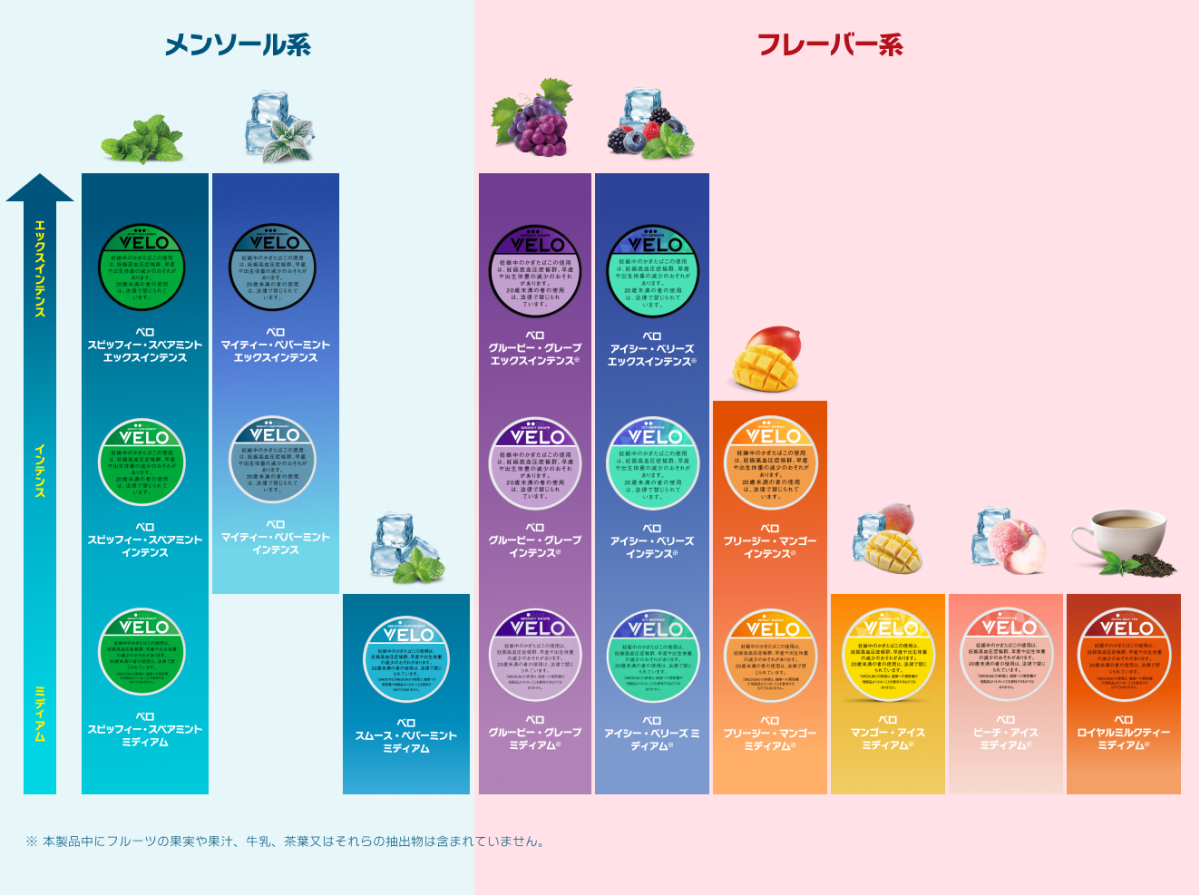
British American Tobacco's Japanese subsidiary, BAT Japan, launched VELO Mango Ice Medium on November 2, 2026, with distribution expanding to selected 7-Eleven, FamilyMart, NewDays and Seicomart stores from November 3. The new oral tobacco product contains 15 pouches per can and retails for ¥380, featuring a mango and cooling flavor profile at Medium intensity. At the same time, BAT Japan raised prices on multiple existing VELO products from ¥360 to ¥380 per can and withdrew selected SKUs from convenience store distribution without discontinuing them entirely. The changes affect product assortment, pricing and retail channel allocation.
product
Nov.04
Zhang Xiaotang Appointed Deputy Director of China’s Tobacco Regulator, Adding Another Finance-Background Official to Top Leadership
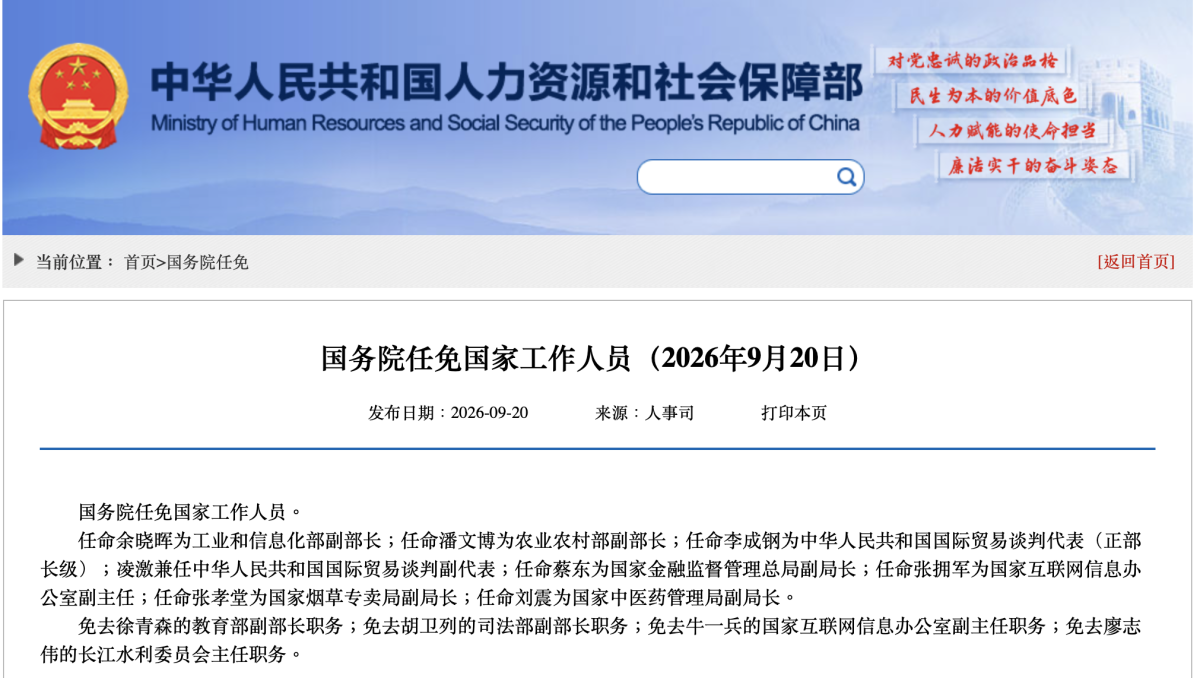
China’s State Council has appointed Zhang Xiaotang as deputy director of the State Tobacco Monopoly Administration, with the regulator’s official website now listing him as a Party leadership group member and deputy director. Zhang previously led Hebei China Tobacco and earlier headed the STMA’s finance and audit department. His appointment follows the elevation earlier this year of former tax official Yao Laiying to head the STMA, adding another senior official with a strong fiscal or financial-management background to China Tobacco’s top leadership in 2026.
News
Sep.20
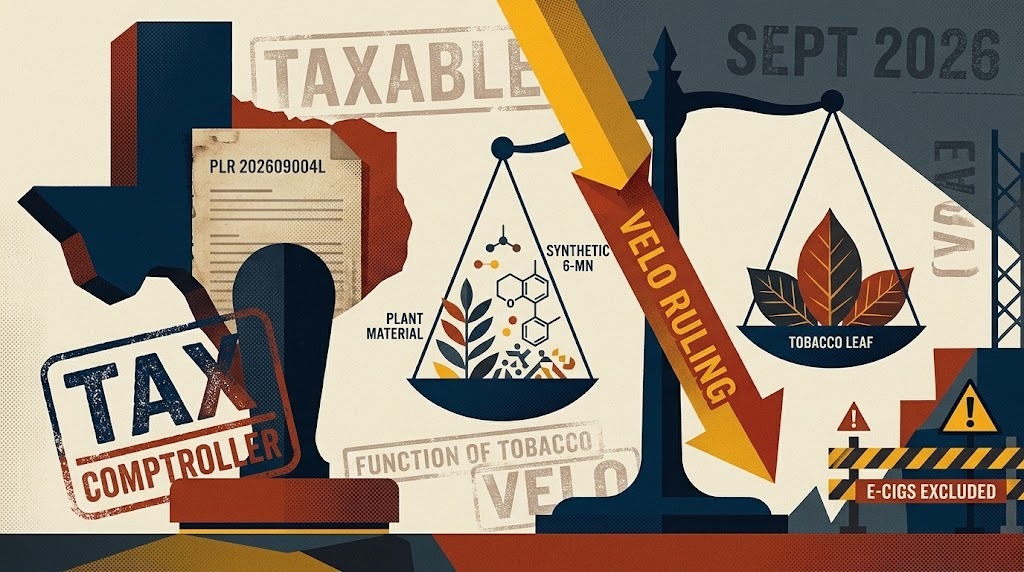
Texas Extends Tobacco Tax Interpretation to a 6-Methylnicotine Product, Citing VELO Ruling
The Texas Comptroller of Public Accounts ruled in September 2026 that a combustible product made with non-tobacco plant material and 6-methylnicotine (6-MN), a synthetic nicotine analog, qualifies as a taxable tobacco product. The applicant said the product contained neither tobacco leaf nor measurable conventional nicotine. The determination applies reasoning from a May Texas Supreme Court decision involving VELO nicotine pouches, finding that the plant material and 6-MN together perform the functions of tobacco in a conventional smoking product. The ruling carries applicable tax, licensing and reporting obligations but is limited to the facts submitted by the taxpayer. It does not establish a blanket tax classification for all 6-MN products or extend the same conclusion to e-cigarettes.
Regulations
Nov.06