Indian Government Implements Penalties for Unregistered Pan Masala and Gutkha

Aug.07.2024
Indian Government Implements Penalties for Unregistered Pan Masala and Gutkha
Indian government to penalize unregistered pan masala and gutkha production, enforcing ISD registration on entities with multiple registrations. (20 words)

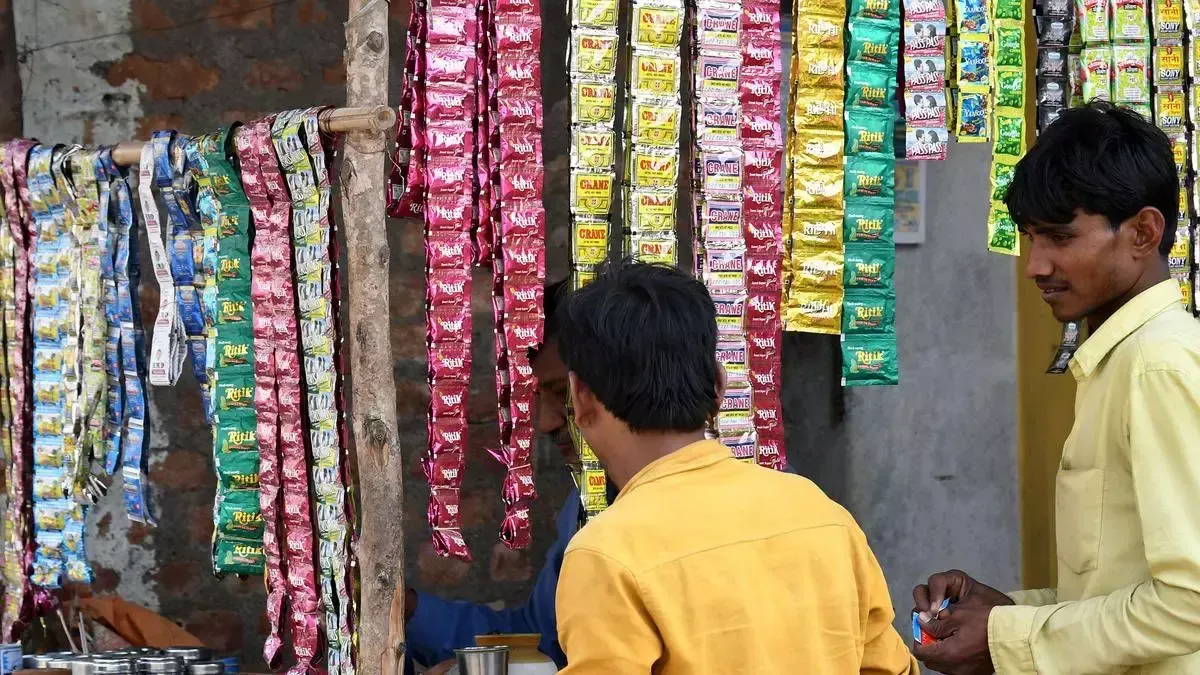
According to a report from The Hindu Businessline on August 7th, the Indian government has announced that penalties will be imposed on specific manufacturers of pan masala and gutkha starting October 1st for not registering under the Goods and Services Tax (GST) system.


Starting on April 1, 2025, entities with multiple registrations will be required to implement an Input Service Distributor (ISD) registration, with fines imposed on those who do not comply.


The Central Board of Indirect Taxes and Customs (CBIC) has notified the date of changes brought by the Finance Act in the interim budget of 2024. As per Section 13 of the Act, manufacturers of pan masala, gutkha, and other tobacco products will be fined 100,000 rupees (approximately $1,191) for each unregistered machine. Additionally, unregistered machines will face confiscation and seizure. However, if the fine is paid or registration is completed within three days of receiving the penalty notice, no confiscation or seizure will take place.


In order to curb tax evasion and in line with the recommendations of the GST committee, the government issued a notification in January requiring taxpayers engaged in transactions involving products such as betel nut and tobacco to provide information. Accordingly, two forms were notified - GST SRM-I and GST SRM-II. The former involves registration and processing of machinery, while the latter asks for monthly input and output information.


The system was originally scheduled to take effect on April 1, but was later postponed to May 15. This program applies to manufacturers of betel nuts, unprocessed tobacco (excluding lime pipes) with or without brand, "shisha" or "gudaku" tobacco with or without brand, tobacco mixtures for pipes and cigarettes, chewing tobacco (excluding lime pipes), filtered chewing tobacco, flavored tobacco, snuff, and branded or unbranded "gutkha" products.


This special program is based on suggestions put forth by the Group of Ministers (GoM). The group has noted that illicit trade in tobacco products is a common international phenomenon and has emphasized the need for alternative systemic enforcement and administrative mechanisms to curb tax evasion and improve compliance. Therefore, it is recommended to implement tracking and tracing methods. This is an internationally recognized practice to combat illicit trade in the tobacco industry, achieved through electronic means. In addition, tobacco product manufacturers are also advised to register each machine and disclose information such as the machine's make, year of production, track number, and machine capacity.


At the 50th meeting, the GST Council proposed the mandatory implementation of the Input Service Distribution (ISD) mechanism to allocate input tax credit related to services acquired by the headquarters but distributed among multiple registered entities. Accordingly, the interim budget has been revised and a designated date has now been notified.


We welcome news tips, article submissions, interview requests, or comments on this piece.

Please contact us at info@2firsts.com, or reach out to Alan Zhao, CEO of 2Firsts, on LinkedIn


Notice

1.  This article is intended solely for professional research purposes related to industry, technology, and policy. Any references to brands or products are made purely for objective description and do not constitute any form of endorsement, recommendation, or promotion by 2Firsts.

2.  The use of nicotine-containing products — including, but not limited to, cigarettes, e-cigarettes, nicotine pouchand heated tobacco products — carries significant health risks. Users are responsible for complying with all applicable laws and regulations in their respective jurisdictions.

3.  This article is not intended to serve as the basis for any investment decisions or financial advice. 2Firsts assumes no direct or indirect liability for any inaccuracies or errors in the content.

4.  Access to this article is strictly prohibited for individuals below the legal age in their jurisdiction.


Copyright


This article is either an original work created by 2Firsts or a reproduction from third-party sources with proper attribution. All copyrights and usage rights belong to 2Firsts or the original content provider. Unauthorized reproduction, distribution, or any other form of unauthorized use by any individual or organization is strictly prohibited. Violators will be held legally accountable.

For copyright-related inquiries, please contact: info@2firsts.com


AI Assistance Disclaimer


This article may have been enhanced using AI tools to improve translation and editorial efficiency. However, due to technical limitations, inaccuracies may occur. Readers are encouraged to refer to the cited sources for the most accurate information.

We welcome any corrections or feedback. Please contact us at: info@2firsts.com
Product | JTI Launches Ploom AURA Teal Electric Pop in South Korea, Its First Dual-Color Edition
JTI Korea launched the Ploom AURA Teal Electric Pop limited edition in South Korea on September 1, 2026, marking the first dual-color design in the Ploom AURA range. The device combines a dark green body with teal accents and is accompanied by matching Front Panel, Back Cover and Pocket Bag accessories. The standalone device is priced at KRW 29,000, with three additional device-and-accessory bundles available. The release continues JTI Korea's use of limited colorways and interchangeable accessories to expand the Ploom AURA portfolio without introducing a new hardware platform.
Sep.03
How Large Is France’s Off-Channel Tobacco Market? Logista Says It Has Become Structural, While the Official Estimate Is 17.7% and Some Industry Studies Put It Above 50%
Logista France says tobacco consumption outside France’s official tobacconist network has become a large and structural market phenomenon, but official and industry estimates differ sharply. France’s TAFE study estimates that 17.7% of tobacco consumption escaped domestic taxation in 2023, with most of that volume attributed to cross-border purchasing rather than street sales. Some industry studies use broader off-channel definitions and put the figure above 50%. Meanwhile, French Customs seized 547.94 tonnes of tobacco in 2025, up 12%, showing continued pressure from illicit trade.
Sep.04
JAMA Study: U.S. Vape Directories Fail to Sustainably Curb Unlisted Sales as Product Shifts May Redistribute Brand Share 2Firsts Recommended
A study by CDC Foundation researchers found no sustained decline in e-cigarette sales across Alabama, Oklahoma and Louisiana, the first three U.S. states to implement e-cigarette directory laws. Louisiana initially saw a significant sales decline, followed by a rebound and a persistent reduction in product availability. Sales also shifted from nontobacco-flavored disposables toward prefilled cartridges, with Vuse Alto driving much of the increase in menthol cartridges. By April 2025, unlisted products still accounted for more than half of e-cigarette nicotine sales in all three states.
Sep.18
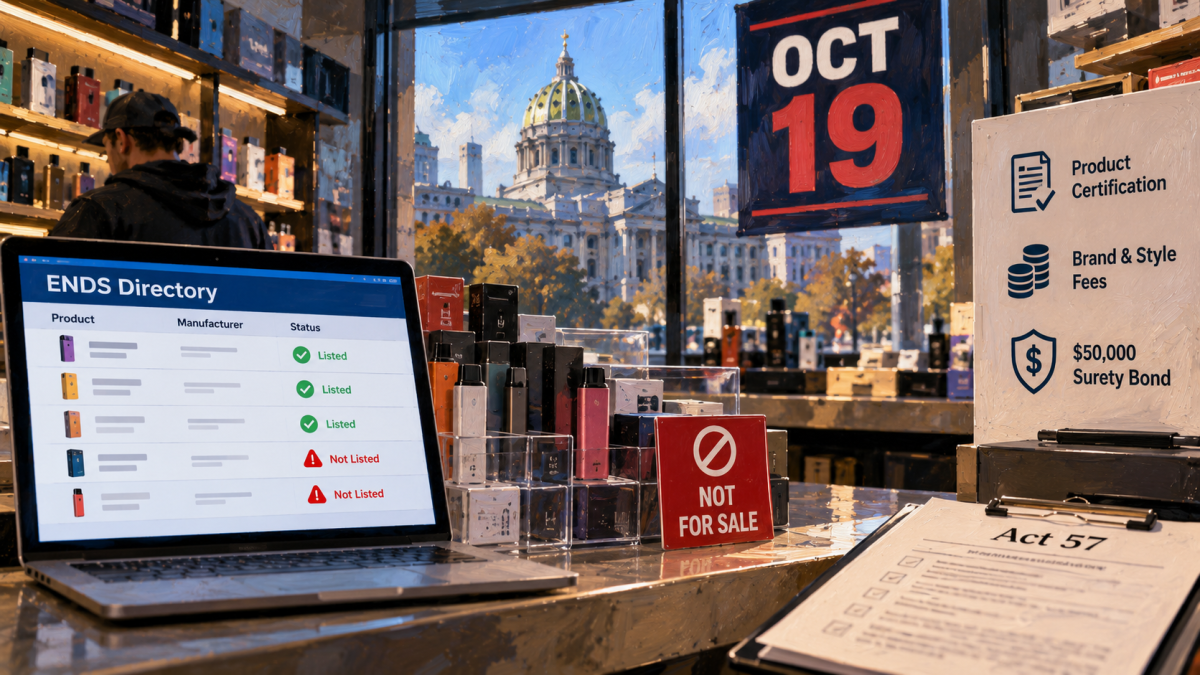
Pennsylvania Vape Directory Enforcement Starts Oct. 19, Barring Retail Sales of Unlisted Products
Pennsylvania's Act 57 vape directory regime will reach the end of its 120-day inventory transition period on Oct. 19. Nicotine-containing e-cigarettes intended for retail sale in the state that are not listed on the Attorney General's ENDS directory will then be barred from retail sale and treated as contraband subject to seizure, forfeiture and destruction. Manufacturers face annual product certification, brand- and style-based fees and a minimum $50,000 surety bond, while retailers and wholesalers must source through licensed channels and monitor the directory.
Regulations
Oct.08
Ireland Raises Nicotine Product Taxes Again as Cigarettes Gain €1 and Vape Duty Is Set to Jump 40%
Ireland has increased tobacco excise under Budget 2027 and announced a further rise in its E-liquid Products Tax. From Oct. 7, the tax burden on a pack of 20 cigarettes in the most popular price category increased by €1, with pro-rata increases on other tobacco products. The government plans to raise EPT from €0.50 to €0.70 per millilitre from Jan. 1, 2027, a 40% increase applying to both nicotine-containing and nicotine-free e-liquids. The tobacco duty increase is expected to raise about €63.1 million in a full year.
Regulations
Oct.09
Smoke-Free Business Hits 42% of Q2 Net Revenue as PMI’s First TNFD Report Covers Single-Use Electronics, Critical Raw Materials and IQOS Repairs
Philip Morris International has published its first report aligned with the Taskforce on Nature-related Financial Disclosures, bringing its electronics supply chain and the use and end-of-life stages of smoke-free devices and consumables into its nature-related assessment. PMI said its smoke-free business accounted for about 42% of total net revenues in the second quarter of 2026. The report says non-circular electronic products, particularly single-use items, can increase consumption of limited natural resources and also details an IQOS repair pilot. A 2040 circularity scenario tests assumptions including a 50% reduction in product waste-related costs, 10% raw-material savings and a 25% substitution rate for refurbished products versus new products.
Sep.23